25% Of Scots Wait 3 Years Before Seeking Debt Help

Christians Against Poverty Scotland have released a new report that shows that 25% of the people that they helped in Scotland waited between one and two years before seeking help with their debts, and a further 25% waited three years or more before seeking help. Worryingly, 45% said that they did not know where to get help. CAP Scotland is a national charity that works with 715 affiliate churches, looking to help the vulnerable people out of poverty, UK-wide.
  • 12% Didn’t wait to seek help.
  • 27% Waited less than one year.
  • 25% Waited 1-2 years.
  • 25% Waited 3 years or more.
  • 11% Unknown
A rise in non-priority debt e.g. credit cards, personal loans and catalogue debts, saw the average debt level in Scotland increase to £17,917, of which £12,065 was identified as being non-priority debt. On average, CAP Scotland clients have 9 non-priority debts and the most common types of non-priority debts their clients reported were personal loan (69%), credit card debts (63%), mobile phone debt (46%), overdraft debt (38%) and catalogue debt (34%). In terms of priority debts, council tax arrears (40%), rent arrears (10%), energy arrears (9%) and mortgage arrears were the common types of debt that their clients sought help for. Low income, mental ill-health, relationship breakdown, long-term illness and unemployment were identified as the most common reasons that caused a debt crisis for their clients. 71% said that debt impacted their relationship, with 19% citing debt stress as the reason for a relationship breakdown. 44% are unable to afford adequate clothing 37% sacrificed meals 37% went without heating 31% are unable to afford basic toiletries 28% said they had considered or attempted suicide as a way out of debt. 20% were unable to afford to light their home. Speaking on the finding of the CAP Scotland report, Gareth McNab, Director of External Affairs said: “The full effects of the global pandemic will not be felt for some time; we know that one in four (25%) CAP clients wait over three years before seeking debt help. The debt advice industry is anticipating rising numbers in need of debt advice. More must be done to reach and help households struggling. Joined-up working is needed more than ever, forming partnerships to combat the financial fallout of the pandemic. Yet we cannot forget that even before COVID-19, households were struggling and, without change, people will still struggle in the future. Unless we do something about it” You can read the CAP Scotland 2021 client report.
As a leading Scottish debt advice company, having helped thousands of people with their unaffordable debt, Trust Deed Scotland® have received over [reviews] reviews on Trustpilot where many people tell us things like “I wish I got help sooner” or “I can sleep again at night, now that my debt is under control again.” The fear of being judged, or feeling ashamed or embarrassed about having debts are often spoken about by our clients in regards to reasons why they put off seeking debt help. In April 2021, Lauren said: “After being hesitant for a while to contact Trust Deed Scotland, I am so glad I did, as Pamela was so friendly, understanding and non-judgemental during the process. I would 100% recommend anyone struggling with financial difficulties to get in touch. I wish I had sooner.” Also speaking in April 2021, Louise said: “Called Trust Deed Scotland eventually after months of worrying about mounting debt and just wish I’d have done it sooner. Soreena dealt with my case and couldn’t have asked for anyone better than her. She listened and totally understood everything I said and never judged me at all. I can now look forward to receiving my wages every month, knowing that everything is going to be paid in one payment and might even have some left now.” Earlier in the year, in January 2021, Jamie said: “I couldn’t have been made to feel more comfortable, I was always quite ashamed to talk about my debt. Vicky made me feel completely at ease and made the whole process seem so simple.”

Help with unaffordable debt in Scotland

If you live in Scotland and you are struggling with your finances, you can find out more about your options by calling Trust Deed Scotland® on 0141 221 0999. Alternatively, you can also download our Scottish debt solutions guide. Our experienced team can give you confidential advice, that with help you understand the pros and cons of all formal debt solutions in Scotland such as Trust Deeds, the Debt Arrangement Scheme and other Scottish Debt Solutions. Once we know more about your situation, we are then able to give you tailored debt advice that fits your individual requirements.
Can I include a Bank Overdraft Debt in a Trust Deed?

Yes, you can include a bank overdraft debt in a Trust Deed. In fact, not only can you include a bank overdraft debt in your Trust Deed, but the outstanding balance will automatically be included as one of your creditors. Sometimes clients that we speak to believe that a bank overdraft isn’t a real debt. Perhaps because they service the debt on a regular basis, as their wages and other income go into the account, it may take at least a couple of weeks before it either starts to become partially overdrawn, or more commonly, reaches the authorised overdraft limit. Bank overdraft debts are one of the more common debts types that will be included in a Trust Deed or DAS (Debt Arrangement Scheme), alongside credit card debts, unsecured loans and many others.

Bank overdrafts are an expensive way to borrow

You may consider that the bank overdraft facility is like a financial buffer for you, a very convenient form of borrowing but it’s feasible that the bank can request full payment of the bank overdraft debt at any time ‘upon demand’ And, most crucially for people who are already struggling with their finances, an overdraft can become a very expensive form of borrowing with penalties and high-interest rates. Research from Compare the Meerkat in August 2020 found that almost 33% of us are relying on an overdraft to get us through the Coronavirus pandemic. The average amount owed on their bank overdraft debt is in excess of £500. In June 2019, UK regulators introduced new rules on overdraft lending to help stimulate a fairer, simpler and more transparent overdraft market. In reality, the move to help people who have bank overdraft debts ultimately backfired as the likes of Lloyds, Barclays, Royal Bank of Scotland, HSBC, Halifax, Clydesdale Bank and others hiked-up their interest rates to almost 40% and up to 50% in some cases. However, since these new rules only started during lockdown when they also instructed banks to offer interest-free overdrafts, many customers of banks may not yet realise that the costs for using an arranged overdraft will be even more expensive than using credit cards.

Payment breaks coming to an end

Where people in Scotland are still furloughed, or have been made redundant and are already taking advantage of payment breaks, replaced by tailored support; expenditure may suddenly become overwhelming. If you are in a payment break that is due to end, our advice is to contact your lender(s) and ask what options you have for tailored support. If you have unaffordable debts in addition to your bank overdraft debt then we would also advise you to speak to a qualified money advisor such as Trust Deed Scotland®. In order to apply for a Trust Deed, all unsecured debts must be included and it is normal that if you bank with a provider who is also a lender, then you will need to open a new bank account with a lender whom you do not owe any money to. The good news is that it’s very easy to open a new basic account while in a Trust Deed, with a number of options open to you. Find out more about the best bank accounts for Trust Deeds. If you have a joint account, then you will need to remember that the other party becomes fully responsible for payment of that debt.

Can you get a new bank overdraft when a Trust Deed has ended?

Yes, once you have completed your Trust Deed, you will be free to start rebuilding your credit again and after a period of credit rating rehabilitation, you will be free to apply for a bank overdraft again. It’s true that bank overdrafts can make our day-to-day lives much easier. An unused bank overdraft may seem like the best option in the event of the ‘rainy day’ that may occur. But there is incontrovertible evidence that bank overdraft debts can once again develop due to poor affordability checks, which become self-regulated. No sooner, have you started to encroach your overdraft limit, than other debts such as credit cards, loans and the cost of living itself can sometimes put you in a precarious position.

What’s the difference between an emergency fund and a sinking fund?

For clients of Trust Deed Scotland® who have gone on to enjoy a brighter future, most often they will take the monthly contribution that they had paid into their Trust Deed and instead create a savings accounts that will be used as an emergency fund and a sinking fund. Essentially an emergency fund is what it sounds like. An allowance to cover a sudden emergency such as car repairs, anything that was unexpected. A sinking fund is more a way of budgeting for expenditure that we know will occur. These may be one-time purchases such as a new computer, or phone. A car, or a deposit for a home. Events such as weddings and graduations, or recurring expenses such as car insurance or Christmas. The added benefit of creating a savings account instead of an overdraft is that you will accumulate interest on the amount. Research online and find a savings account that suits your circumstances. While the easy answer may appear to be the account that offers the higher rate of interest, in real terms, these savings accounts are offered with penalties for early withdrawal etc, so always do your homework on them before committing.

Help with bank overdraft debt in Scotland

If you’re worried about bank overdraft debt in Scotland, or indeed any other type of debt – you can contact Trust Deed Scotland today for qualified advice. We offer expert debt help in Scotland and have helped over [volume] people in Scotland since 2009. Thousands of people have left debt advice reviews where our clients tell us in their own words that our advisors are friendly, non-judgemental and that our advisors were able to find a solution to their debt problems quickly and efficiently.

What debts does a Protected Trust Deed include?

The type of debts that can be included in a Protected Trust Deed are generally those that are described as unsecured, with some exceptions. When you enter into a Protected Trust Deed in Scotland, most of your unsecured debts will be included and this may include:
  • Credit Cards
  • Personal Loans
  • Overdrafts
  • Catalogues
  • Gas and Electric Arrears
  • Council Tax Arrears
  • Payday Loans
  • Store Cards
  • Buy Now Pay Later Agreements
  • Any Other Outstanding Personal Bill e.g. Vet Bills
There are other debts that can be included in Trust Deeds, but we recommend contacting us today confidential advice as it’s important to understand not only the debts that you have and whether or not debts those can be included in a Protected Trust Deed, but also other aspects include your affordability, total debt owed and your income vs. expenditure. On some occasions, an alternative Scottish debt solution may be more beneficial for you.

What types of debt are excluded from a Protected Trust Deed?

Typical debts that aren’t included within a Protected Trust Deed include:
  • Mortgages
  • Secured Loans
  • PCP and PHP Agreements
  • Hire Purchase Agreements
  • Court Fines
  • TV Licence Arrears
  • Student Loans
  • Child Support Arrears
You can also find out more about the differences between secured and unsecured loans, if you’re unsure what this means.

Can joint debts be included in my Protected Trust Deed?

A joint debt in Scotland is a debt that has your name and the name of the other person you entered into it with on the agreement. A joint debt can be included in a Protected Trust Deed, however, the other person named on the debt will still be responsible for making payments towards it. This is also true of guarantor loan debts in Scotland. If you have some of the debt written off, the other person will still be asked to pay the remaining money back, therefore that debt isn’t written off in the same way that the other debts that included in the Protected Trust Deed would be written off. If you have joint debts, and are thinking about applying for a Protected Trust Deed, you should contact us for confidential advice first. We can let you know how it would affect you and the other person named on the debts.

What happens to my debt during a Protected Trust Deed?

Before Trust Deeds are agreed, proposals are put to the creditors who monies are owed to. If the creditors agree to the Trust Deed, you’ll make monthly payments towards the Trust Deed for 48 months, or 60 months if this was agreed as an extended duration for the Trust Deed. When your Protected Trust Deed has been complete, you’ll be discharged. At this point, any balances outstanding on the debts included in your Trust Deed will be written off.

Is a Protected Trust Deed right for me?

To find out if a Protected Trust Deed is right for you, we advise you to try our online Trust Deed Wizard® tool. This will begin the process of finding a debt solution for you, based on your own unique circumstances. When you’re looking at the types of debts that can be included in a Protected Trust Deed, you may have debts that can be included such as those owed to family and friends but you may benefit from speaking to Trust Deed Scotland® in order to find out the advantages and disadvantages of doing so. There are alternative solutions to Trust Deeds in Scotland, one of which is the Debt Arrangement Scheme. When you speak to an expert money advisor, all pros and cons will be explained to you, and sometimes the type of solution that fits your needs best may not be a Protected Trust Deed after all. When considering your decision on whether a Protected Trust Deed is right for you, we have previously written articles in response to questions we’ve previously been asked such as Is A DAS Worth It? or Is A Trust Deed A Good Idea? Trust Deed Scotland® has thousands of reviews on Trustpilot, however, we also offer Debt Arrangement Scheme and Sequestration advice, which means you will be given balanced, fair advice that puts you in control of the decision-making process.

Is A Trust Deed A Good Idea?

Is A Trust Deed A Good Idea?

Trust Deeds help thousands of people in Scotland manage their unaffordable debts and reduce their monthly debt repayments to an amount that they can afford to repay on a regular basis. However, Trust Deeds aren’t a solution suitable for everyone and there are alternative debt management solutions in Scotland that can be just as effective or better. You can read more about how a Trust Deed works and the criteria within that link, or you can apply for a Trust Deed online, right now. The decision to proceed with a Trust Deed is based on you, your affordability and what is best for your long-term financial stability, rather than whether a Trust Deed is a good idea or not. Get in touch with Trust Deed Scotland® today and you’ll receive a personalised illustration.

Affordable Monthly Repayments?

The solution(s) open to you will largely depend on how much debt you have and how much you can afford to repay on a regular basis. If you have already defaulted on debts such as credit cards and loans, you may be familiar with income and expenditure guidelines, or budget sheets sent to you from your creditors. The same guidelines are largely available from debt charities and Money Helper websites. These budget sheets will ask you to write down a list of your income and expenditure details and what you usually spend on priority bills such as mortgage/rent and council tax.  These will also include what you spend on travel expenses per month, clothing and many other expenses Whatever monies are leftover is known as your disposable income. These are the funds that you have leftover to repay your debts. A debt charity service or a company such as Trust Deed Scotland® have the experience of advising on the acceptability criteria for these guidelines for these and can work with you to find out any hidden expenses that you may not take into account, and establish what your true disposable income is. This is important because if you are to enter a Trust Deed, or any other form of debt management solution, you will be making a commitment to repay a regular amount over a number of years. Where you fail to keep up the repayment of your Trust Deed, you could end up with a failed Trust Deed, ultimately leading to you being potentially sequestrated. More importantly for you, you would be no better off than when you first sought advice. This is where the experience and trustworthiness of your debt expert is important. Trust Deed Scotland® have advised over [volume] people since 2009 and have gathered thousands of five-star Trust Deed reviews on TrustPilot. We pride ourselves on our commitment to compliance and training. We genuinely want the best outcome for our clients and always have their best interests at heart.

Alternatives to a Trust Deed?

The Debt Arrangement Scheme is a popular alternative debt solution available to residents of Scotland. It’s a statutory debt repayment plan which also uses legislation to allow you to freeze interest and charges and bring your debts under control. There are advantages to the Debt Arrangement Scheme:
  • Personalised debt repayment plan based on your situation
  • Monthly payments will be based on what you can afford
  • Interest on your debt will be frozen
  • Protection against creditor action.
  • Assets protected meaning you will not be asked to sell your house, or your car.
  • Your Money advisor deals with creditors on your behalf.
There are also disadvantages of the Debt Arrangement Scheme:
  • May last longer than the typical 48 months offered by a Trust Deed.
  • Subject to certain conditions. Includes making all payments towards your Debt Payment Plan and paying your monthly expenditure and bills when they fall due. If you fail to make payments, your plan could be revoked.
  • Unable to obtain credit or use an overdraft while you are in a Debt Payment Plan.
  • Credit rating will be affected.
Depending on the severity of your situation, Sequestration may be the best way for you to resolve your debts. On the other hand, a debt consolidation loan or negotiating debt repayment plans directly with your creditors may also be better for you. Refer to our article regarding is a DAS worth it for further information on this solution.

Advantages of Trust Deeds?

There are many advantages of Trust Deeds, a few of which are:
  • Pay back what you can afford.
  • Your Trustee will deal with creditors on your behalf.
  • You will be protected against creditor action.
  • On the successful conclusion of a Trust Deed, your remaining debt will be written off.
  • If you own assets such as a property, you agree with your Trustee in advance whether the Trust Deed affects them.
  • You may be able to remain as the director of a Limited Company.

Disadvantages of Trust Deeds?

  • Your credit file will be updated to reflect that you have signed a Trust Deed. This information will remain on your credit file for six years.
  • As a result of this, you may find it difficult to get credit for a period after your Trust Deed is finalised.
  • For a Trust Deed to become protected, you must convey all your assets to your Trustee. That includes any property that you own. In certain circumstances, it may be possible to exclude your property, but you need to get clear advice on this when you speak to a debt advisor.
  • As mentioned earlier, failure to keep up with repayment of your Trust Deed could result in you being sequestrated. Therefore, it is important that you re fully aware of the Pros and Cons of a Trust Deed and that the amount you repay is realistic for all parties.

Can You Have 2 Trust Deeds?

If you have already been through the process and came out the other end then yes, you can get a Trust Deed twice. If you’re currently in a Trust Deed with a different company then you may also be able to get a second Trust Deed but there are some conditions attached. You can find out more about the process involved in our article on how to get a Trust Deed twice.

How to Get Trust Deed Advice?

If you really want to know if a Trust Deed is a good idea, seek tailored debt advice today. We’re open from 9am to 8pm during the week, and selectively during the weekends. If you do something about your debt today, you don’t need to worry about it tomorrow. Reputable debt advice companies and debt charities are regulated by governing bodies, this should help ensure that you are not ‘sold’ into a Trust Deed and that you are fully aware of the pros, cons and alternatives. Remember, a Trust Deed may not be for you, but that doesn’t mean that you are beyond help. The sooner that you seek help, the sooner you can begin to understand what options are open to you. You can also learn more a similar question of Is DAS Worth It? which investigates the Debt Arrangement Scheme in a similar fashion to the article above of the merits of whether a Trust Deed is a good idea.

Best Bank Accounts For Trust Deeds

You can operate a normal, basic bank account during a Trust Deed or DAS in Scotland – Entering into an arrangement doesn’t stop you from having a basic account. However when you’re exploring options for the best bank account to have while in a Trust Deed or DAS there are some considerations. You may need to switch to a new bank account before the Trust Deeds starts. The two main reasons for needing to switch bank account:

Frozen Bank Accounts & Bank Account Closures

Some banks may choose to freeze your bank account if you enter into a Protected Trust Deed or Debt Arrangement Scheme. Banks monitor insolvency registers. However, your bank account is more likely to be frozen if you owe the same bank money, and in that case – a tactic known as ‘setting off’ is more likely to be used.

Setting-Off

The term ‘Set-off’ describes a bank taking money from one account to repay another. They do not need to seek permission fro you to do this. This is a commonly used tactic where you had a credit card or personal loan with the same company that you have your current account with. You may, or may not also have an overdraft facility with that company; expect that to be removed also. You can avoid set-off by moving your current account to a bank that you do not owe money to. A frozen bank account will leave you unable to pay your household bills and other priority bills so it is therefore important that you seek advice on this.

What Do I Need To Open A Basic Bank Account?

You’ll normally need proof of identification and proof of your address in order to open a new bank account when entering a Trust Deed. Proof of identification includes:
  • A passport
  • A photocard driving licence
  • A letter confirming your benefit entitlement
  • HMRC tax notification letter
You can then use one of the following documents for proof of your address:
  • A driving licence (either new or old)
  • Your TV licence
  • A recent electricity or gas bill
  • A recent council tax bill
  • A recent letter about your benefits
  • A recent letter or statement from another bank
If you don’t have a passport or photocard driving licence you may need to ask the bank what types of ID that they’ll accept before you try and open an account with them.

What If The Bank Won’t Let Me Open An Account?

Banks can’t use your credit rating as a reason not to give you a basic bank account. However, they don’t have a legal obligation to provide you with one either. They’ll normally prevent you from having a bank account if you’re an undischarged bankrupt. I.e. you’ve only just Sequestrated yourself. Or if there’s any record of fraud on your credit file. If you’ve applied for an account and a bank has turned you down, you need to make sure that they were assessing you for a basic account rather than a current account. However, as a leading provider of debt advice in Scotland, fortunately – Trust Deed Scotland has experience of this and we can, therefore, recommend the best banks to open an account with prior to entering a Trust Deed.

Recommended Best Banks In A Trust Deed

Before committing to a Trust Deed, a personalised illustration should be carried out to find out who you owe monies to and any potential solutions that you may qualify for. Our current list of recommended banks for individuals entering Trust Deeds are as follows: Many people we’ve spoken to  ask us which is the best bank account for bad credit and its more important that you ensure that it’s a basic bank account rather than a current bank account. Whether you have a good, or poor credit rating is not as important when seeking a bank account that you can use in a Trust Deed. There are also some lenders who specifically advertise bad credit bank accounts and these usually come with a chargeable amount. Therefore, if you decide to open up a new bank account, it is recommended that you consult with an expert debt advisor beforehand, in order to get a better understanding of your options.

Joint Bank Accounts In A Trust Deed

You can continue to use a joint bank account during your proposed debt solution. However, there will be a financially associated link, so this is perhaps best avoided if the other person has a good credit rating.

Dealing With Bank Account Issues While In Debt

If you have debt with your bank or you’ve had money taken from your account to cover a debt, let us know and we’ll help you to find out what your options are. You can try our Trust Deed Wizard tool to get started, or give us a call on 0141 221 0999. We’re here to help and will always have your best interests at heart.

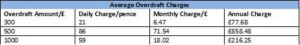
How Much Are Overdraft Fees Costing You?

If you find yourself relying on your overdraft regularly, you are not alone but it’s important to remember that it is a form of debt and you are being charged overdraft fees for the privilege of using it. Average interest rates increased from £2 per month in 2008 to £12 by 2013 and last year it was reported that banks increased their rates further, some even tripling the previous rate.

If you need help with your finances, Trust Deed Scotland may be able to help. Try the Trust Deed Wizard now to find out more.

There are several steps you can take to see if you could save money on exorbitant overdraft charges:

Set up low balance alerts

Some banks give you the option to receive a free text alert when you are close to going into your overdraft. If you find yourself forgetting to check your balance which results in you going into your overdraft from time to time it may be a good idea to make use of this service to stop you accidentally becoming overdrawn.


See our testimonials for hundreds of independently verified reviews showing how we’ve helped customers get their finances back on track by entering Trust Deeds.


Check if your overdraft is charged monthly or daily

You may only get charged for the days you use your overdraft, so if you had a negative balance for a few days while waiting to be paid, you would only pay a fee for these days. You may, however, be charged monthly. This means that you would be billed at a flat rate for the month, whether you used the overdraft for just a few days or the entire month.


There are simple steps you can take to get your finances straightened out

Move direct debit dates

If you find yourself running short of cash around the same time each month and you have a direct debit due around that time, contact the company and see if you can change the date the direct debit date. This could be the difference between needing to dip into your overdraft or staying in credit.


There is a lot of conflicting information available about your finances. We have dispelled common myths about bad credit to help you make an informed decision.

Change your current account to one with lower interest fees

Look around at the options available to you. Your current bank may offer an account with more attractive overdraft rates or perhaps changing to another bank is your best option. Some accounts have a monthly usage charge but include no or low interest overdrafts in the cost. Depending on how much your overdraft is costing you at the moment and if you use it regularly, you may you save money by going for this type of account.


Average overdraft charges
Annual Overdraft Charges – click to enlarge.


To find out more see our Scottish Debt Help page or Contact Trust Deed Scotland for more information.