Who Are Trust Deed Scotland?

When people are looking into getting help with their debts, they may or not know already know who Trust Deed Scotland®  are, what are Trust Deeds, the Debt Arrangement Scheme or alternative Scottish debt solutions in Scotland and whether the solutions offered may seem that they are ‘too good to be true’.

If you’ve been experiencing financial difficulties as a result of a recent change in your circumstances, or you’ve been in debt for a number of years; we’re offering solutions that means you’ll make lower monthly payments, protect your home and car, and write off debt you can’t afford to repay – in as little as 48 months…We appreciate how this may sometimes seem too good to be true.

You can find out more about Trust Deed Scotland and our story of how we became the No.1 rated debt relief company in Scotland.

The first thing you may or may not know about who are Trust Deed Scotland® is that we’ve helped over [volume] people in Scotland since 2009.

In-House Team – We don’t sell your details on. You will remain with Trust Deed Scotland® from the moment that you make your first enquiry until after you have been successfully discharged.

Some websites that you find on Google, social media and elsewhere are known as lead generators. This means that you may be passed from pillar to post and whilst the GDPR has resulted in better data protection all round, there are a number of companies who will use your details for their own end, and the companies that they work with ultimately concentrate on the solutions that result in more money for themselves.

Trust Deed Scotland® pride ourselves on providing balanced debt advice that explains the risks and benefits of Trust Deeds, the pros and cons of the Debt Arrangement Scheme and the advantages and disadvantages of any other alternative solution you may qualify for.

We’re aware of other organisations who use pushy sales tactics, we’re also aware of a number of copycat companies pertaining to be Trust Deed Scotland

Over [reviews] 5 Star Reviews – More than anyone else in our industry, we’ve collected on the independent reviews platform Trustpilot. The reviews that we’ve curated highlight in our client’s own words, the type of service that we’ve given them, and how the solutions have impacted their lives.

We understand that there still is a stigma attached to being in debt and that it can be difficult to take the first steps of asking for help.

Therefore whenever anyone leaves us a review, not only does this indicate that we’ve provided an ‘excellent’ service which we’re immensely proud of but it also helps to display a level of trust bestowed upon us by individuals who were in a similar position to anyone who is still considering if Trust Deeds are legit.

98.6% Trust Deed Acceptance Rate – If you apply for a Trust Deed you will be made aware of the likeness of the Trust Deed / DAS being approved. You will always be kept up to date and informed of your Trust Deed / DAS application, every step of the way and we will work with you to explain and overcome any issues, of all available solutions.

As the No.1 rate debt advice company, with the experience of helping over 25,000 in Scotland – this is where our years of experience help us to drive successful outcomes for our clients.

Scottish Heritage – Many of the organisations that offer debt advice in Scotland offer it as a bolt-on to solutions offered in England, Wales and Northern Ireland. We’re proud to be owned and operated in Scotland, with the correct experience and knowledge to offer these solutions in Scotland.

There are many differences between Trust Deeds and Individual Voluntary Arrangements as one example, that those companies based elsewhere simply don’t have the same level of expertise.

No Setup Fees – Unlike some other companies, we do not charge setup fees or any other upfront costs for our services. The purpose of asking for help with debts is to get your life back on track and work towards a brighter future. Adding fees and charging you for debt advice doesn’t help you and doesn’t sit right with us. We’ll always have your best interests at heart.

70% Debt Write Off Possible – Affordable monthly repayments are one of the biggest advantages to both Trust Deeds and the Debt Arrangement Scheme, and by using our Trust Deed Wizard tool and calculating fair expenses, we are able to reduce the amount that our clients repay every month.

For example – This means that if you were previously paying £909 every month to your debt payments, we can reduce this down to £273.

Regulated Debt Advice– We’re proud of our internal record of giving our staff the highest levels of training and support. However, we’re also officially authorised by regulatory bodies to give debt advice.

Trust Deed Awareness Campaigning – We’ve been actively making people aware of Trust Deeds and alternative solutions for a number of years, across TV campaigns, radio and many other places.

This may help you to understand how much your monthly Trust Deed payment will be, or how much you may be expected to pay under the Debt Arrangement Scheme and the agreed Debt Payment Programme. However, in addition, you will have a clear plan to get your finances back on track.

Ultimately, if you’re interested in learning more about who are Trust Deed Scotland®, then you can contact Trust Deed Scotland® today for debt advice. Our main debt advice helpline is 0141 221 0999, or you can try our Trust Deed Wizard® tool to start the process now.
Hiding Debt From Partners During Coronavirus

If you have been hiding your debt from a partner during the Coronavirus pandemic, you are not alone. Even before the Covid-19 outbreak, many people across Scotland had been hiding personal debts problems from their partners. In 2017, relationship charity Relate said that an estimated 14% of people are hiding a debt problem from their partner. The same report found that 25% of the respondents would typically argue with one another about debt and other financial issues at least once in a fortnight. In 2018, a report by the Money Advice Service found that 44% of a poll of 4,000 people were keeping their debt a secret and that the average debt being hidden was over £4,164. Credit card debts, personal loans and bank overdrafts are the most common types of debts that we hide from our partners with almost 48% hiding at least one credit card debt from their partner.

Are You Hiding Debts From Partners During Coronavirus?

It’s actually quite common for people to successfully complete a whole Trust Deed term of 48 months or finish their Debt Arrangement Scheme without ever telling their partner about their debt issues. Although Trust Deed Scotland would usually advise against hiding debt from your partner. Hiding a debt problem from our friends and family is more manageable when we are operating under normal circumstances  however, the effects of self-isolation during Coronavirus mean that most of us are spending more time together, finding less time for ourselves and finding it more difficult to ‘nip out to make a quick phone call’ Trust Deed Scotland, Scotland’s leading debt advice company has been continuing to provide assistance to individuals in Scotland struggling with debt during the crisis and found that many people are continuing to hide debts from their loved one, even under stricter lockdown conditions. Hiding your debts under a heightened stressful situation such as the Coronavirus may prevent you from seeking help – it may also prevent you from attaining a mortgage payment break, or credit card payment breaks due to the fear of your partner finding out about the total debt you have and the perceived fear of a backlash as a result. If this is the way you are feeling, we would recommend that you get in touch with an expert debt advisor as soon as possible, in order to find out what your options are. All advice is offered by qualified experts and it’s always confidential.

Why Do People Hide Debts?

There are many reasons why people in Scotland might choose to hide unaffordable debts from the people closest to them. Those reasons may include guilt, embarrassment or not wanting to burden their partner with stress. Sometimes the reasons for hiding debt could be more serious. E.g. as the result of gambling debts or other addictions. In these instances, hiding debts is only part of a bigger problem and means the causes of debt are less likely to be solved.

Domestic Violence Fears

On some occasions, people also hide debts from their partners for fear of domestic violence. If you have experienced domestic abuse during the Coronavirus pandemic, or at any other time – we recommend that you look at the Safer Scot website. It is a Scottish Government priority to ensure that anyone who is a victim of domestic violence gets access to the support services they need during these unprecedented times. Scottish Women’s Aid is operating a 24-hour helpline during the crisis, with support being offered by webchat and email as well. Scottish Women’s Aid and Police Scotland have said officers would treat domestic abuse cases with the same seriousness as they did before the pandemic, and that victims could still leave their homes to seek refuge. Another aspect of domestic abuse is known as financial abuse. This is a term used to describe cases where a partner or family member exerts excessive financial control, harm or exploitation of another. Victims find this difficult to talk to their friends and family about this, and financial institutions often fail to acknowledge financial abuse, according to the Citizens Advice Bureau. Domestic violence has reportedly increased 120% since the introduction of lockdown measures.

Why You Shouldn’t Hide Debts From Your Partner

Having debt is a burden on our minds that carries extra weight and the stigma of having debt often makes people attempt to struggle on alone. Opening up about our debts and talking to us closest to us can help take some of that stress away immediately. It’s even possible that a partner, or family member can help pay off the debt, or a chunk of it that will enable you to get back on your feet. Or more commonly, you can work together to resolve outgoings by spending less each month on the items that are non-essential. However, talking about our debts creates more trust in our relationships, provides fewer secrets and above all else, a sympathetic, friendly ear that can listen to your issues and give you extra security in sharing an issue. Where you still feel this isn’t an option – you can approach a charity such as Breathing Space. Trust Deed Scotland

Why You Shouldn’t Lie About Your Debts

Admitting your debt issues doesn’t make you a weak person. The opposite in fact – it means you’re willing to tackle the problem head-on rather than hide from it. Many of the independent debt advice reviews received about Trust Deed Scotland talk about these exact same issues that prevented our clients from seeking helped and we would often encourage opening up to your family and friends about your financial difficulties. Whether you simply created debts due to excessive charges from credit card debts and unaffordable personal loans – lying about debts to those closest to you is never recommended – the stress of having debts in itself can be unbearable but adding extra pressure on yourself by being deceitful in any relationship can add to that burden.

Opening Up About your debt to your loved ones

As a company that has helped over [volume] look forward to a brighter future, Trust Deed Scotland have spoken to many people from all walks of life. Of all the five star debt advice reviews that we receive, more and more people are saying that they’ve made an enquiry with us due to a recommendation from a friend, or family member. When people openly discuss their debt issues and signpost reputable sources of debt advice, it helps to dispel the taboo people have about debt itself and then encourages more people to seek help about their own situation.

Unaffordable debt issues happen to the best of us

Debt issues most often occur as a direct result of a change in circumstances. Long-term redundancy, sudden health issues. Relationship issues among the many reasons. Even just spending that spired out of control. It’s very rarely intentional but once debt gets to the stage where it becomes unaffordable, this is where people begin to feel embarrassed and ashamed at getting into the situation.

I’m worried about my unaffordable debt, what should I do?

If you’re worried about your ability to pay off your unaffordable, unsecured debts you should seek expert debt advice. Our team of Scottish debt specialists at Trust Deed Scotland® have helped over 20,000 people in Scotland with their debt problems. Our expert, non-judgemental advice is personalised to your situation. To get started, give us a call on 0141 221 0999 or find what Scottish debt management solutions are open to you. Try our Trust Deed Wizard®

What Happens When A Trust Deed Finishes?

When your Trust Deed comes to an end, your Trustee will issue what’s known as a ‘letter of discharge’. A copy of the letter of discharge will be sent to Accountant in Bankruptcy (AiB), the regulatory body of Trust Deeds in Scotland and the Register of Insolvencies will record your Trust Deed discharge. If you enter a Trust Deed, typically you’ll finish your repayment in 48 months, as long as you made all payments in your plan. Depending on your circumstances, you may have entered into a Trust Deed for an extended period of 5-6 years. Over the term of your Trust Deed, you’ll have made a number of affordable monthly payments – and this will count as ‘full and final settlement’ of the unaffordable debts included in your Trust Deed. At the end of your Trust Deed term, any unsecured debt that you weren’t able to repay during your Trust Deed will be written off. When you are discharged from a Protected Trust Deed, you will be discharged from any outstanding debts from the people you owe money to (your creditors) that you had included at the date you registered your Trust Deed. This means that your lenders are no longer allowed to pursue money that was owed to them when you signed the Trust Deed. However, some debts won’t be written off such as a student loan, or any court fine.

What Happens With Secured Debts After A Trust Deed?

If you owe money that is secured against an asset such as property or a vehicle, it won’t be included in your Trust Deed. Your secured lenders won’t be consulted on whether they agree to your Trust Deed, and they won’t write off monies that you owe them, whether you complete your Trust Deed term or not. However, the fact that you’re in a Trust Deed should make the secured payments easier to make, as your Trust Deed payments would be calculated not to take up any monies that you need for your typical essentials – not just your rent or mortgage, but utility bills, travel expenses and so on. If you’re a homeowner, you might be required to release some equity from your property, so you can repay your unsecured lenders more of what you owe them before they write off the rest. However, you may find that the impact of your Trust Deed on your credit rating makes it harder to release equity. Mortgage providers can see that you’ve entered a Trust Deed, so you might find that it’s harder to get a new mortgage deal, or that you’re charged a higher rate of interest if you do. If you can’t release any equity then your Trust Deed could be extended by 12 months.

Trust Deed Credit Score And History Impact

Information about Protected Trust Deeds and defaults will remain on someone’s credit reports for up to six years after they occur, so they are likely to remain on someone’s credit history even after they have been discharged from their Protected Trust Deed, which normally lasts for 4 years. If you’ve already defaulted on your credit agreements even before considering a Trust Deed, this too will be logged on your credit score.

How Will A Debt Arrangement Scheme Affect My Credit Rating?

When your Debt Payment Programme (DPP) is approved, you’re placed on the DAS register. This is coordinated and managed by the DAS administrator and is available to credit rating agencies. This register, along with other insolvency registers, is added to other information to your credit report, which calculates your credit score. Just like a Trust Deed, or even a simple default notice, the Debt Arrangement Scheme will affect your credit rating for at least six years. However, this may be extended further depending on how long it takes you to pay off your Debt Arrangement Scheme in total. E.g. if you are on a DPP for under 6 years there is no difference, or if you are going to repay a DPP for longer than 6 years; your debts will not be marked as satisfied until the debt has been repaid at the end of the DPP.

What is a Default Notice?

A default notice is usually sent when you’ve missed or paid less than the full amount for three to six months. The default notice will give you at least two weeks to catch up with any missed payments. If you can do this your account will carry on as normal. If you can’t pay the missed payments in this time your account will default. Default notices only apply to debts which are regulated by the Consumer Credit Act, such as credit cards, payday loans, personal loans and store cards. You’ll know a default notice has been served on you when you receive a letter informing you of a ‘Default notice served under section 87(1) Consumer Credit Act 1974’. The most recent revision of this act was in 1983, long before the evolution of the current Trust Deed legislation and the Debt Arrangement Scheme. As the wording of the default notices is quite old, you may, therefore, be directed towards Trading Standards and/or a solicitor – remember this is somewhat outdated legislation and you are advised to instead contact a qualified debt advisor, or debt charity instead. Unless you can get a default notice removed within 2 weeks, this will be recorded on your credit profile for six years. Depending on your lenders criteria, this may have the same affect as a Trust Deed or a Debt Arrangement Scheme registered against your name.

Can You Rebuild Your Credit After a Trust Deed?

Yes, it is possible to begin to rebuild your credit rating after your Trust Deed has finished. Eventually getting a mortgage after a Protected Trust Deed is achievable. It may not always happen immediately and will require a bit of work – it is certainly possible for most people to successfully be approved for a mortgage after a Trust Deed. Also, it will not be possible to obtain a re-mortgage on a home that is still in the Trust Deed, without the Trustee’s permission, until they have discharged their interest. A Trustee’s interest in a property can continue even after the debtor is discharged. It may be that the lending terms are not as favourable as before, however by showing a commitment by making regular payments to utility bills, and by using credit sensibly, purely for the purpose of rebuilding your credit score, you will in time secure a more favourable lending rate. Paying utility bills by direct debit can help rebuild credit after a Trust Deed and even just joining the electoral roll helps prospective lenders build trust in you.

A Brighter Financial Future

Many people in Scotland have approached Trust Deed Scotland® after they’ve put off seeking help over their unaffordable debts for a number of years. So severe are some people’s financial difficulties, that if minimum payments were made only; it may take them longer than two decades to clear their outstanding debts. If you’re struggling with debts and making minimum payments to debts such as credit cards, you may regard protecting your credit score as being more important to you than dealing with the debts you have. This isn’t uncommon. However, anyone pondering the pros and cons of the impact of entering a formal debt management solution may have on their credit score after a Trust Deed finishes should look towards the long term outlook and whether it’s better to essentially press the restart button, or continue on alone waiting for a solution to present itself in another form.

Want Trust Deed Advice?

If you feel you’re struggling with debt, seek tailored debt advice today. If you do something about your debt today, you don’t need to worry about it tomorrow. As well as Trust Deeds and Debt Arrangement Scheme, there are other alternative Scottish debt solutions. Trust Deed Scotland® are able to offer no-obligation, confidential advice on all debt management methods available in Scotland. Call us on 0141 221 0999 or try our Trust Deed Wizard® tool to get started today.

Burns Night 2024 Rabbie Burns Debt

25 January marks Burns Night, when in Scotland we celebrate the life and work of Robert Burns, usually with Haggis, Neaps and Tatties and with a dram of Whisky. But beyond the Selkirk Grace, there’s a sadder side to the life of one of Scotland’s most famous sons that we don’t hear much about. Problem debt can happen to anyone. Rabbie Burns died owing debt. His income was £100 per year. His overall indebtedness was £110 per year. He had amassed unaffordable debts in a bid to promote his work and then tragically fell ill meaning that he couldn’t work on his farm and was unable to pay off his creditors as a result. In today’s terms, this means that his income was £7,676 per annum and his debt total was £8,443 per annum, owing to 6 creditors according to Dr Clark McGinn who researched this while writing a book on the poet. Find out more about the poetry of Rabbie Burns on the Poetry Foundation.

Why Was Rabbie Burns In Debt?

Sadly, if Robert Burns dreamed of a brighter financial future, this dream would never be realised. In fact, it was written that even on his death bed, he had to borrow money from family friends to pay off a tailor who had been harassing him over payment of a military uniform. Like many great artists like him, his work was never fully recognised while he was still alive and therefore never received his royalties. Rabbie Burn’s story is not unlike that of many people in Scotland today, where a loss of income due to a period of sickness results in an insurmountable debt total. Indeed, many of the 25,000 people that Trust Deed Scotland have given advice to over the years had the same difficulties and cause of their debt. Unlike Rabbie Burns, those people that we’ve helped have been fortunate enough to manage their current predicament and look forward to a brighter future. If you do something about your debt today, you don’t need to worry about it tomorrow. Many people have left us a Trust Deed Scotland review where they speak about their own experiences and reasons that they got into debt in the first place. Our experienced debt advisers have spoken to people from all walks of life and provided confidential, non-judgemental advice.

Rabbie Burns Debt Legacy?

There’s a tragic irony that for a man with so little wealth to his name whilst still alive, that his face would be used upon our Scottish banknotes as a modern tribute and that the Clydesdale Bank would use the quote ‘I’ve seen the Oppressor’s cruise smile amid his hapless victim’s spoil‘. It’s perhaps fitting that in one of Burn’s most famous poetry works, To a Mouse, he wrote: “The best laid schemes o’ mice an’ men Gang aft a-gley, An’ lea’e us nought but grief an’ pain For promis’d joy.” Whether you celebrate Burns Night or not, there’s something in this line that we can all relate to. If you are finding that you’re worried and stressed over your debts, it can be hugely uplifting to take the first step of seeking help. You may be able to take comfort in knowing that If you do something about your debt today, you don’t need to worry about it tomorrow. Call us on 0141 221 0999 or try our Debt Calculator to find out what options you may have to get help with your debts. Our experienced debt advisers will be able to give you information on the pros and cons of all available debt solutions in Scotland including Trust Deeds, the Debt Arrangement Scheme and alternatives.

Glasgow City FC Trust Deed Scotland

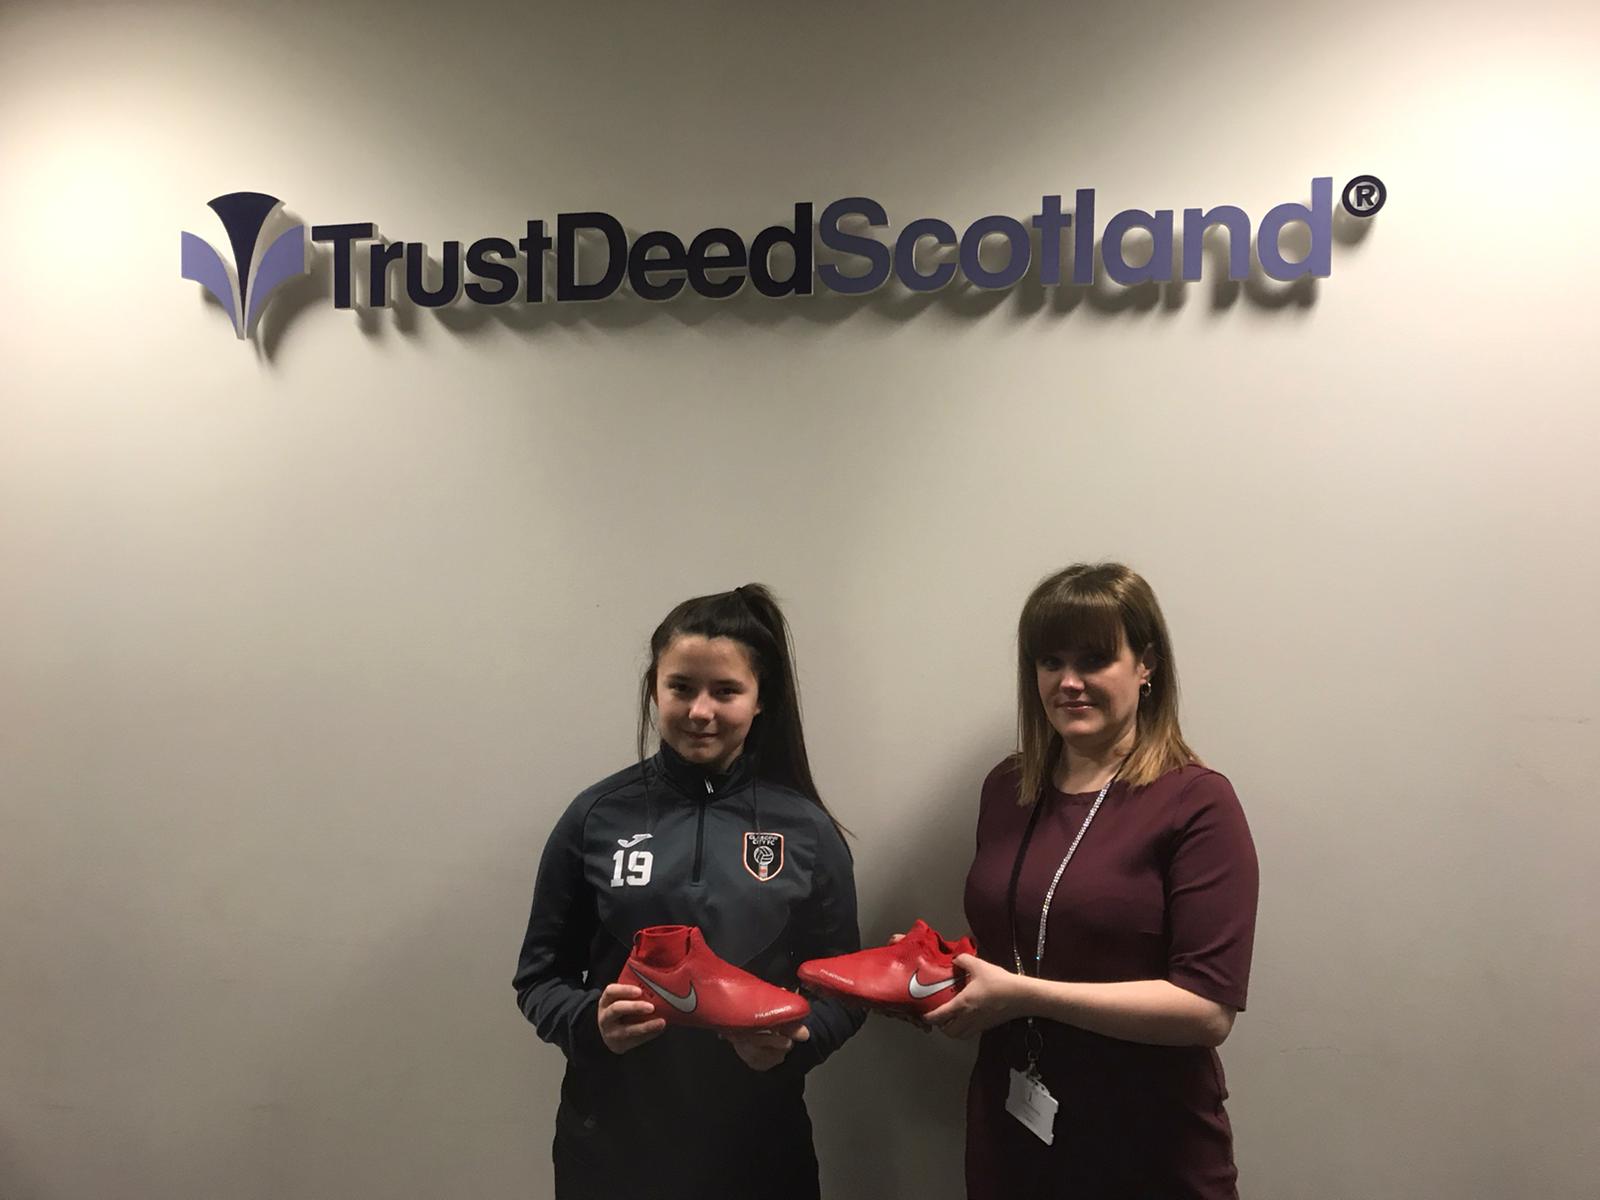
The Trust Deed Scotland Foundation have been working with Glasgow City FC and their recent Boot Sponsorship initiative.

As part of the initiative, u15s NP player Kaylin Winchester will receive boots for the upcoming season.

The Glasgow-based organisation based at Petershill Park in Glasgow, were founded in 1998 and are an amateur club who depend on sponsorship and partnerships.

As well as an adult women’s team dominating their domestic league and performing admirably in European competition, Glasgow City FC have a number of youth teams competing in categories from as young as under 9’s training across the city.

Why Funding Amateur Sports In Scotland Matters

It is widely believed that participation in sport creates economic and social impacts on society that extend beyond the behavioural changes experienced by individuals taking part. Scotland has over 13,000 sports clubs, 900,000 members and almost 200,000 people dedicated to volunteering in sport. As well as fun and enjoyment, sports clubs bring great benefits to people and society.

Trust Deed Scotland is delighted to support the expansion of Scotland’s sports clubs through support for volunteering, accessible facilities and funding to enable more women, minority ethnic communities and disabled people to participate.

Research shows that 1 in 5 people are living in relative poverty. John Dickie of the Child Poverty Action Group in Scotland wrote “As s time slips by, childhoods slip by, childhoods blighted by the simple fact their families just don’t have the money they need to give their children a decent start in life.

“These aren’t just statistics. These are children going hungry, missing out on school trips, unable to enjoy the activities and opportunities their better-off peers take for granted. These are parents going without meals, juggling debt and seeing their own health suffer to protect their children from the poverty they face”.

[table id=customer-survey-2024-postcode /]

Dump Your Valentine’s Day Debt

A recent survey from money.co.uk highlighted that almost half of Brits would put themselves into debt to pay for an engagement ring, which is staggering considering that the average engagement ring bought in Britain is priced at between one to three month’s salary. The same data showed that it takes between 2-5 years to pay off this debt, and that’s before the happy couple even begin to plan their wedding. But with the staggering ever-increasing commercialism of Valentine’s day, it’s the little expenses that add up. Restaurants, gifts, and entertainment. Stick it on the credit card, worry about it later. Take out the buy now pay later option offered by the likes of Klarna. Trust Deed Scotland® recommends that in any situation regarding your finances, that you budget accordingly. If you don’t think you can afford it, don’t buy it. From the Shetland isles all the way down to Galashiels and Dumfries and Galloway in the borders, many people in Scotland are experiencing personal financial difficulties. In what’s been described more recently in the media as ‘Problem Debt’ it’s important that you seek help as soon as possible if you can’t cope with your debts. Hiding debts from your partner It’s not uncommon in Scotland for people to hide debts from their partners. And, in cases where there is no existing joint debt, or guarantor loans exist; many people have gone through a whole Trust Deed term of 4 years or more, without ever mentioning anything of their debt to family and friends. However, Trust Deed Scotland® would advise that you to open up to your closest friends and families for emotional support at the very least if you do have debt problems. By browsing our thousands of reviews on TrustPilot, there are many cases where it was a friend or family member that made a recommendation for Trust Deed Scotland® and our debt advisory service, which is staggering considering we’re all too aware of the stigma attached to having debts. A stigma which sadly does mean that many people feel alone and too embarrassed to talk about their finances. Our advisors understand the courage it takes for someone to face up to their problem debt, they have a friendly, empathetic approach and are non-judgemental, it’s perhaps this difference that results in someone feeling empowered enough to talk openly about how their unaffordable debts, rather than struggling on alone carrying the burden of their debt with them. If you do something about your debt today, you can stop worrying about it tomorrow. By reducing your monthly repayments to one, affordable payment, stopping the pressure created by creditors’ constant phone calls and red letters, the reduction in anxiety and stress caused by your debt problems could result in a better life for you and your loved ones. People suffering stress tend to ‘lose touch’ with their partners or lose emotional availability and this itself can result in relationship issues for those stressed out over money worries.  We recommend speaking to Breathing Space if you are feeling down on 0800 838 587, or find help from SAMH on 0141 530 1000 if you are feeling this way, regardless of whether you have debt or not. However, it’s not all about extravagant spending on Valentine’s Day Another recent survey from the US showed that expensive gifts are a turnoff for as many as 1/3 of the respondents, which should bode well for us Scots since we’re not known for splashing out on presents. Perhaps, a handmade card and a homecooked meal are suffice enough for our partners!

Beyond Valentine’s Day – Concerned about your debts?

You can get expert, confidential debt advice from Trust Deed Scotland® by calling us on 0141 221 0999. If you complete our online Trust Deed Wizard®, this can allow you to find out if you would qualify for a Trust Deed, Debt Arrangement Scheme or any other debt solution in Scotland. Our expert advisors can talk to you about your debts and your affordability and then make recommendations based on the facts, including the pros and cons of any applicable debt solutions.  

How To Deal With Debt Stress

Dealing with Debt Stress

Trust Deed Scotland knows through speaking to thousands of people for many years, that debt can be a heavy burden. A heavy burden that causes stress for people from all walks of life. Whether you’re considering a Trust Deed in Edinburgh, a Debt Arrangement Scheme in Glasgow, or you have a couple of credit card debts in Dundee. You may be a lawyer in Aberdeen, a call-centre operative from Galashiels or a Dentist from Oban; no matter what your race, culture, ethnicity, creed, class and nationality – stress and debt affect everyone, indiscriminately. From talking with our clients we know that debt has been on their minds 24/7; impacted their everyday decision making; forced them to go without essentials and in many cases led to social isolation. 50% of British adults with a debt problem have a mental health problem and 25% of adults with a mental health problem have a debt problem. The link between stress-inducing debt and the nation’s current mental health crisis is clear. We’re here to help people struggling with debt and want to help you to manage your stress on your journey towards a brighter future.  

Debt and Mental Health Scotland – The ‘Missing Link’

  If left unchecked, stress caused by debt can become a gateway to more serious mental health issues. We echo the opinion of the Money and Mental Health Policy Institute who believe that debt is the ‘missing link’ between financial and mental health problems. From our research, here are the 8 most shocking findings:
  1. People in Debt have been bracketed as a ‘high-risk’ group in terms of potential mental health problems – alongside children in care; drug users and prisoners.
  2. Debt has a stronger correlation with mental disorders than low income.
  3. Those in debt are 3x more likely to suffer from depression.
  4. Levels of anxiety increase in parallel with credit card debt levels.
  5. People with debt are 4x more likely to still have depression after 18 months of treatment than those who have no debt and sought treatment.
  6. Financial disagreement is the most common cause of divorce. Those who disagree about finances almost every day had an estimated 69% increase in the hazard ratio of divorce relative to those who never argue about finances.
  7. Around 2.4 million children live in highly indebted households in the UK. Amongst these children: 58% said that they worry about their family’s financial situation, and nearly 20% said they had been bullied at school as a result of lacking things their peers had.
  8. Unsecured debt is likely to have a greater influence on psychological well-being than secured debt.

How Does Debt Cause Stress?

  The stress of having too many credit card debts, unsecured loans and the daily grind of typical expenditure can make people feel a range of emotions from feeling sad, sick or overburdened by the thought of having debt. Most people feeling stressed out over debts are usually underperforming at work, in the home and in the bedroom and a spiral effect is caused by a lack of real sleep. Something that becomes a common occurrence is the number of people who tell Trust Deed Scotland that they wish they had sought debt help in Scotland sooner.  

Managing Debt Stress?

  If stress from debt has become unmanageable the best advice is to tackle your debt head-on, but there are also some stress management techniques you could try. These suggestions are by no means exhaustive and if you’re dealing with more serious mental health problems, please seek help from a medical professional.  Firstly, you could take some time for yourself and channel your stress into exercise. This may seem somewhat cliché advice, but the benefits of physical exercise and training for your mental health (as well as physical, obviously) are well documented. Physical exercise reduces cortisol and dopamine and releases serotonin chemicals in the brain – which essentially make us feel happier and more positive. Challenging physical training gives you something to focus your mind on, and in the case of weight lifting, or boxing, it offers a release of anxiety, frustration and other negative emotions. When you’re feeling stressed, you may find exercise helps you to focus your mind on a challenge besides your debt. When it comes to addressing your debt problem, clarity of thought is absolutely crucial when it comes to coming up with the right plan of action. Mindfulness could also help you to properly process and release debt stress. To be ‘mindful’ means to pay attention to the present moment, instead of your past mistakes and regrets or becoming overly-worried about the future. More specifically, mindfulness will help you to acknowledge your thoughts and feelings as they arise from moment to moment, without any analysis or judgement. The great thing about mindfulness is that you can practice it for hours at a time in meditation, or on the go throughout the day by focusing on your breathing and surroundings. Mindfulness can help you to manage stress in everyday situations, to the benefit of your overall mental health. As a starting point, Headspace and Mindful.Org offer a range of short meditations you can use at your convenience. BeMindful also offers a complete, free, beginners’ course which lists the key benefits of mindfulness as follows:
  • Feeling less overwhelmed
  • Improved sleep quality
  • Feel more positive with greater self-compassion
  • increase your ability to manage difficult situations
  • Reduced levels of stress, anxiety & depression
  • Reduced overthinking
 

Still Feeling Weighed Down?

  Ultimately, mindfulness, exercise and any other stress management technique can prove insufficient at a certain point. The best solution for reducing debt stress is to tackle the problem at its root and eliminate your debt. As a starting point, our blog is full of useful tips, as a starting point consult our guides on how to clear your debts like a pro and how to budget. Should these methods and budget plans still leave you in an overwhelming position you may wish to consider a more head-on option. For tailored debt advice from experienced debt advisers, give us a call today on 0141 221 0999 or find out if you qualify for a debt solution. This could be your first step towards a brighter future.

Cambuslang Colts Sponsored By Trust Deed Scotland

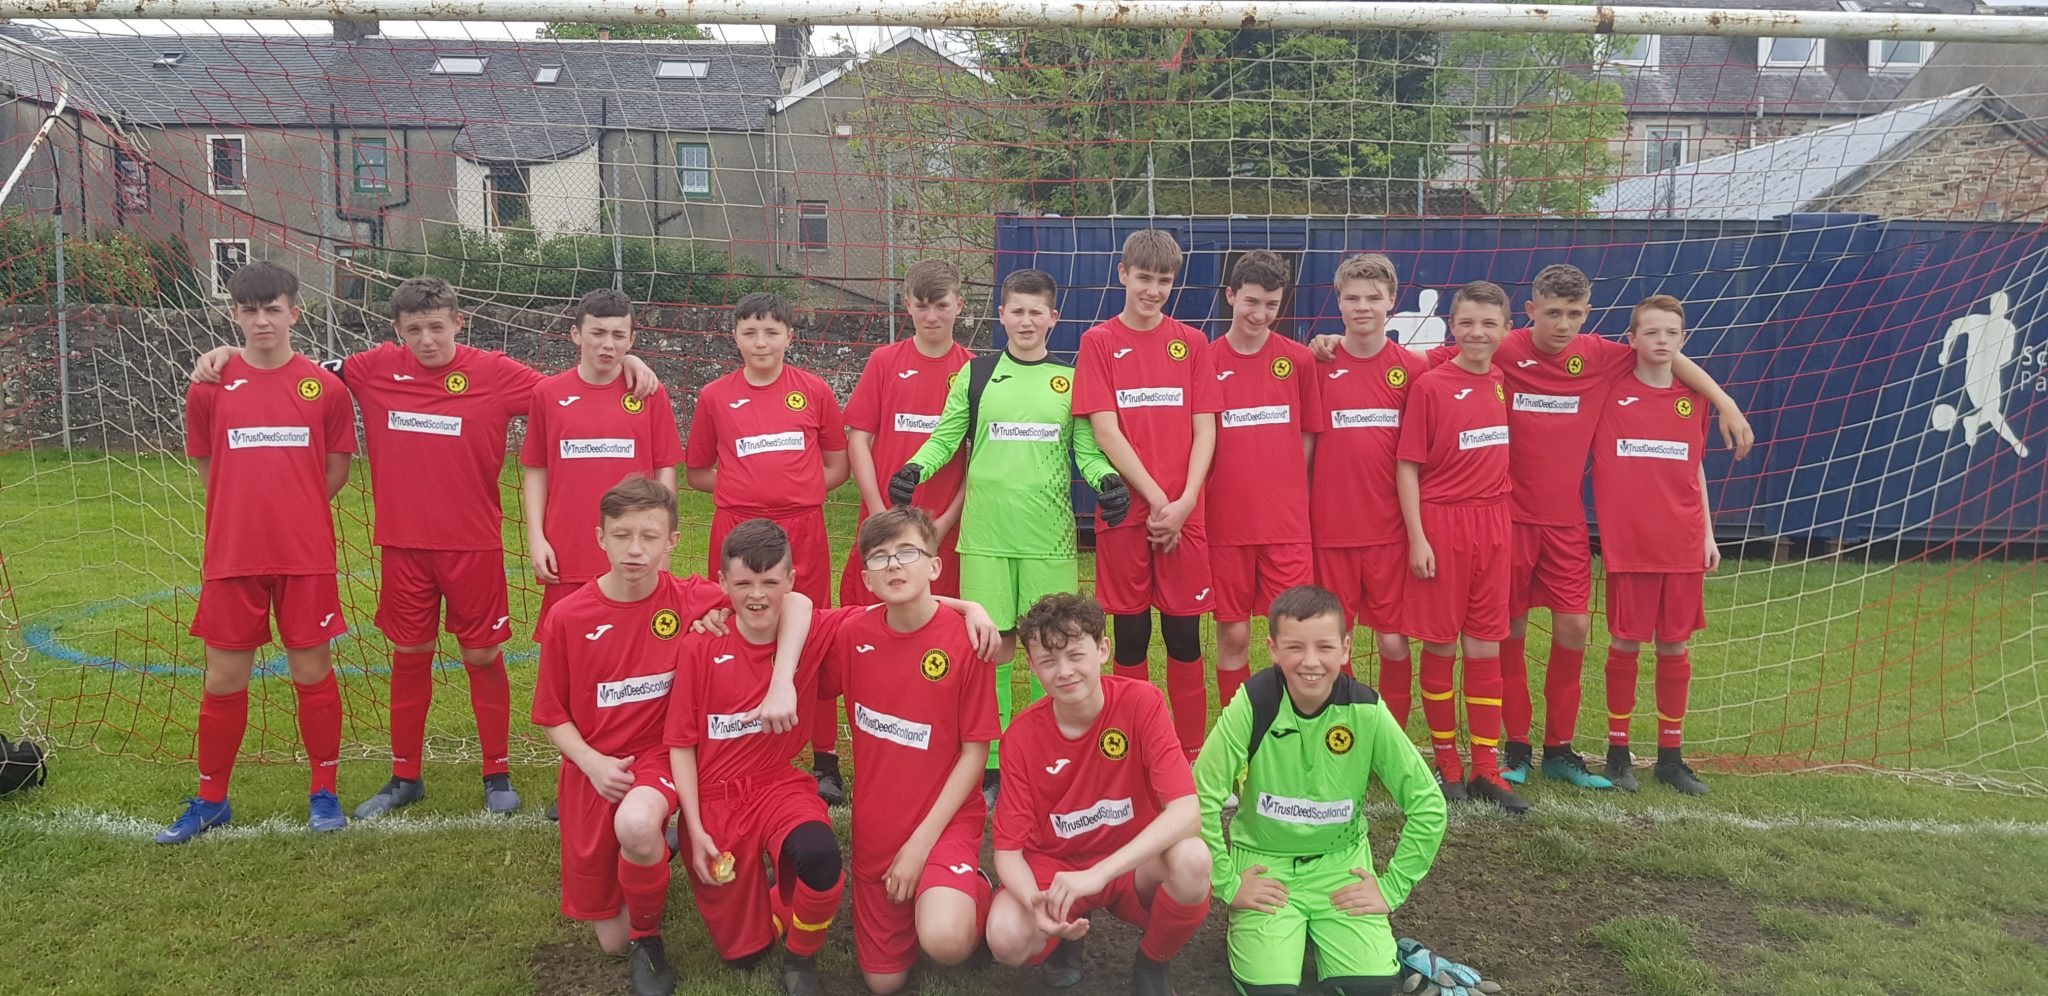
As part of our Trust Deed Scotland Foundation charity, we were recently delighted to sponsor the local youth football team, Cambuslang Colts 2005s.

The team – who play in the Glasgow and District Youth Football league – was established by Chairman Danny Griffin in 2007.

Danny Griffin, who is also a referee for the Scottish Football Association, set up Cambuslang Colts FC to give children and young adults in the local area, a chance to play football and enjoy activities that help to keep their hearts and minds focused on positivity.

Danny said:

“As a club, we try to do things as cost-effective as possible, so that the parents aren’t paying over the odds for their children to play football.

Our sponsors allow us to help families that may not be able to afford kit otherwise. So many families in Scotland live under the menace of poverty and it’s with immense pride that we’re able to give the community something back.

At Christmas, we also try to give back to those in the local community struggling financially through the food bank.”

The young team’s sponsors help to provide free match, training and waterproof kits as well as social trips for the children

Throughout the season, the team enjoys trips to places like Manchester City, Ibrox Stadium, Celtic Park Stadium, Hampden, Craig Tara, Broadwood Stadium, the home of Clyde FC, Skegness and even Barcelona.

The team was surprised with their new Trust Deed Scotland football strips at their first tournament in Strathaven last week where they placed third. Well done lads – best of luck in your upcoming games!

You can donate to the Colts here.

How To Beat Bill Increases: Top 6 Hacks In 2020

Every year ‘National Price Hike Day’ sees millions of UK households hit with price increases on a wide range of bills. Around 11 million households on standard variable tariffs saw their bills go up by an average of £117. Such increases and price fluctuations are not uncommon and can happen regularly. Be it from your energy provider, the DVLA or on council tax, the last thing you need when you’re struggling to make ends meet is a bill increase. The good news, however, is that although bill increases are inevitable: they are not unavoidable. With some strategic thinking and a bit of research, you may be able to beat them – making some savings and easing the pressure on your finances. How you say? Read on for 6 pro tips, hacks and tools to help you beat bill increases this year and beyond.

1. Find the dates for your diary

Number one in our guide on how to beat bill increases. Fail to prepare and prepare to fail -planning is everything. First and foremost it’s crucial that you know when you can expect a bill increase and who with. April 1st marks the start of a new financial year and many companies and government departments will introduce price increases in line with annual inflation on this date. So, this is the main date for your diary. On top of this though, a lot of energy and service providers send out a lot of spam mail in the post, be sure to at least skim through all correspondence and keep an eye out for any notifications about a price increase. Each time you do see one, take a note of the date and provide so you can plan to beat the price hike well in advance.

2. Identify saving areas and shop around

  Number two in our guide on how to beat bill increases. Some increases like council tax, water bills and vehicle tax are harder to avoid, so it’s important to focus on the costs that you can control. There are an abundance of these and plenty of savings to make. Customers who have been with the same provider for energy, TV and broadband networks and mobile phone contract providers for years are almost certainly paying too much. There are hundreds of great deals out there if you shop around. Various apps with built-in comparison services, such as Emma and Moneysupermarket.com that will do the hard work for you and find the best deals for your circumstances.

3. Start with your phone – ask for a better deal

Number three in our guide on how to beat bill increases. There’s a good chance that you’re reading this article on your phone and that’s exactly where you should start. In April: EE increased their prices by 2.7% whilst O2 and Three raised theirs by 2.5%. This has led to an average increase of £9.72 a year. Phone contracts and service provision is a highly competitive market, and under new Ofcom rules, you can cancel your contract with a free text, and ask your new provider to switch you within one working day. This can be very convenient, but we still advise that you get on the phone and haggle the old-fashioned way. Find a quote online for a contract and service similar to yours with another operator and call your provider. Ask for the disconnections department and relay the details to them. In truth, ‘disconnections’ is actually the customer retention department. Faced with losing a customer, their operators are trained to pull out all of the stops to keep you with them. From here, if you are even close to the expiry of your contract and seem serious about changing providers, they will likely offer you an improved deal.

4. Compare Energy Suppliers

  Next, you should turn your attention to your energy provider for our fourth hack on how to beat bill increases. The UK’s main energy providers have raised prices by at least 10%. As such this is probably the area where you are overpaying most and where you could make the biggest savings. For starters, try This is Money’s comparison tool, or the Cheap Energy Club tool – compare the results you get with your last bill. A lot of smaller providers have not decided to raise prices this year and there is a good chance, especially if you have been with your provider for years, that they could offer a better tariff. As a little motivation: should you find a new provider, the cheapest deals for typical users are around £835 per year, meanwhile those on a standard tariff typically pay around £1,083 (UK Average). That’s an average of £21 more that could be in your pocket every month!

5. Satellite TV Packages

  Old habits die hard and Sky TV and Virgin Media has been household essentials in the UK for over 20 years.TV & Cable savings weigh in as our fifth tip to beat bill increases this year. An average rise of 5.1% in prices, averaging out at £3.50 a month is, therefore, most unwelcome. But times appear to be changing, and there are a lot of viable alternatives out there now, hence the turn to cheaper, on-demand services like Netflix. TV packages are much like phone contracts – the marketplace is highly competitive and providers, therefore, place a lot of emphasis on customer retention. As a starting point, you should compare broadband and TV prices online and grab a quote for Amazon Prime or Now TV, following the same haggling process we detailed above.

6. Road Tax and Car Insurance

  Lastly, in our sixth hack to help you beat bill increases this year, short of switching to an electric car, road tax increases are pretty unavoidable, unfortunately. The good news though, is that there are still some savings to make with regards to your car insurance. You should never auto-renew your car insurance. Loyalty is expensive: car insurance companies take advantage of the fact that most customers would like to avoid the effort changing insurer, and so they charge a higher premium every year. If your renewal is coming up, consult all of the main price comparison sites: Comparethemarket.com; Go Compare; Confused.com; and Moneysupermarket.com. As ever, it is more than worth your time to get on the phone to your current insurer and haggle. You could also look into multi-car deals, adding responsible drivers, reconsidering add-ons and more. Pro tip: Money Saving Expert has pinpointed the exact day on which you should buy car insurance.https://www.confused.com/campaign/car-insurance/car-insurance-25 They analysed over 18 million quotes and found that thousands of customers lose money by buying a policy too far in advance, and ‘last-minute losers’ pay well over the odds for waiting too long. By renewing your insurance exactly 21 days (three weeks) before your current policy expires, you could make savings of up to £600. Read their full Car Insurance Renewal report.

Beating Bill Increases – We’re Here to Help

  If you’re struggling to make ends meet and pay your bills, we can help. We’ve helped over 20,000 people struggling with debt and know first hand how small expenses like these can add up over time – making it easy to lose control. If this applies to you, our team of friendly, expert advisors, are waiting for your call. As heard on radio in Scotland and as seen on television, promoting our Trust Deed TV awareness campaigns. We are debt advisers for the people of Scotland. We are here for you if you are in an unmanageable financial position and can talk you through your options.You could join the thousands of Scottish residents who we’ve helped reach a brighter future. For a confidential chat with a member of the debt advice team, get in touch today on 0141 221 0999.

Trust Deed Scotland Supports Action Medical Research

Amanda Hendry, Manager at Trust Deed Scotland has donated work time to Action Medical Research to assist with the fundraising element of their recent Killer Heels & Cocktails Ladies Lunch. The event raised the amazing amount of over £30,000 which will help them to continue funding medical research and make a difference in tackling premature birth, helping children affected by disability and tackling rare diseases in children. Action Medical Research representative, Cecilia Cooper made the following comment  “None of our work would be possible without the support of our volunteers who give up their time to ensure our events are run successfully. EDIT – December 20202 – You can help Action Medical Research in their recent campaign to raise £1 million to fund vital medical research for children in the fight against COVID-19 by donating to their campaign online.

Who Are Trust Deed Scotland?

Trust Deed Scotland are the No.1 Trust Deed Advice company in Scotland, having helped over [volume] people in Scotland and achieving the rank of #1 debt advice company in the UK, based on over [reviews] reviews on the independent reviews platform TrustPilot. As Scotland’s no.1 rated, our dedicated advice team offer help to understand and implement statutory debt solutions such as Scottish Trust Deeds and the Debt Arrangement Scheme. Scottish Trust Deeds: What happens next? Debt Arrangement Scheme: What happens next? The Glasgow-based organisation have a proud history in Scotland, find out more about Trust Deed Scotland.