Category: Debt Help Stories
Trust Deed Specialist Forum
Looking for a Trust Deed Specialist Forum in an online world where advice is offered freely can be overwhelming and often contradictory.
Similar to whenever we feel under the weather, where it’s easy to consult with Google and self-diagnose ourselves with a critical illness, when in fact all we have is a common cold.
The same principle applies to those searching for a Trust Deed Specialist Forum, or any other Debt Advice Forum for that matter.
Unfortunately, it’s all too easy to find yourself in debt and you’re not alone. Often, it’s tempting to bury your head in the sand and hope your problems will go away – but debt isn’t a problem you can just ignore, with interest charges stacking up, the longer you do, the worse your financial situation will get.
For people struggling with debt in Scotland, several debt solutions could allow you to repay what you owe and potentially write off all, or part of your unaffordable debt.
But for true specialist Trust Deed advice, the first step Trust Deed Scotland recommends is to talk to an experienced debt adviser who can talk through all available Scottish debt solutions with you.
One of the options available to residents of Scotland is a legal agreement called a Trust Deed.
What is a Trust Deed?
Many people find themselves with unaffordable debt and do not necessarily know the types of solutions open to them. Therefore, the question of What is a Trust Deed? is fairly common among those in the research phase of their debt help journey. A Scottish Trust Deed is a voluntary legal agreement between you and the companies you owe money to. When you enter into a Trust Deed, your total debts are all grouped together and a Licensed Insolvency Practitioner takes on the role of a trustee. By grouping all of your debts together your trustee will help you to find an amount you can realistically, afford to pay towards your debts. This will become one monthly payment replacing all of your existing payments. Because this amount is based on what you can reasonably afford it is usually significantly lower than your previous combined payments. You’ll make this payment once a month, for 48-60 months depending on circumstances months. At the end of this time, any remaining, qualifying, unsecured debts will be written off. Legally, your creditors can no longer pursue you for the remaining amount. Almost all unsecured debts are eligible to be included in a Trust Deed, such as credit and store cards, unsecured loans including payday loans, overdrafts, old council tax arrears and old utility bills from a previous address, catalogues and old HMRC debts.Advantages of a Trust Deed
- Your debt becomes manageable – You will only make one monthly payment to your Trust Deed rather than several payments to several companies. This monthly amount will be based on what you can realistically afford and is therefore usually, significantly lower. You can agree on a regular date to repay the money you owe, for a time that suits you best – after payday for example.
- No further action – If the majority of your creditors don’t object to the Trust Deed terms it will become ‘protected’ meaning as long as you stick to the agreed terms they can’t legally take actions such as arresting your wages, or bank account to recover money. You can protect your house and car.
- No direct contact from your creditors – The licenced Insolvency Practitioner will take on the role of trustee, who is there to help you to repay your debts.As long as you make the reduced monthly payment, with Protected Trust Deeds your creditors can no longer call you up, email you or contact you directly in any way.
- Your future interest charges can be frozen – After signing a Trust Deed, you’ll be paying back the debt you already owe but not racking up any more debts as you go.
- Debt written off – At the end of your Trust Deed period, any remaining qualifying, unsecured debts will be written off. Legally, your creditors can no longer pursue you for the remaining amount.
Are there any disadvantages to Trust Deeds?
Before considering a Trust Deed, there are some things to be aware of:- You must be able to make the agreed monthly payments towards your debts unless your circumstances change. If they do you need to inform your trustee immediately.
- If you gain any new money or assets such as tax rebates or inheritance during your Trust Deed period your trustee can claim them towards your debts.
- A Trust Deed will negatively impact your credit rating for 6 years from the date you start one, making it more difficult to obtain credit such as a mortgage.
- Usually, you can’t be a director of a limited company. If you are self-employed you may have to appoint a new director or sell your business.
Are there Trust Deed alternatives?
Yes, you can pursue other forms of debt management in Scotland. The Debt Arrangement Scheme also allows to get your payments down to an affordable level and uses formal legislation, the same way a Trust Deed does. When you request Scottish debt help from a reputable firm, they would go through your details and advise you of the pros and cons of all solutions, but more important to you; how they would affect you based on your own circumstances. Always be careful that a company isn’t trying to force you into a solution. If in doubt, it doesn’t hurt to ask around and get advice from multiple firms who are regulated by UK regulatory bodies. It doesn’t harm you to look at the number of specialist Trust Deed forums online, or MoneyHelper – which an independent service set up to help people manage their money.Is a Trust Deed right for me?
If you are thinking of setting up a Trust Deed you should seek advice first, remember you should never pay for this advice, we offer confidential, experienced advice. You should also consider whether you have enough disposable income to afford the monthly repayments. If you’re not sure, it’s something we can help you with. A Trust Deed could be a good option if you:- Have unsecured debts of £5,000 or more
- Have enough income left after paying your bills each month to make a contribution towards your debts
- Have no disposable income to put towards your debts and no assets
- Have debts that don’t exceed £5,000
- Have enough disposable income to pay off your debts before 4 years
How can we help you?
From our feedback, we know people often feel too embarrassed to take that first step and talk about their debt. There’s no need to feel embarrassed and struggle alone. Watch our videos below and see how we can help you.Trust Deed Specialist Forum
At Trust Deed Scotland, we’re the leading Scottish debt advice company in the debt relief category of TrustPilot. We offer non-judgemental and 100% confidential advice to people living in Scotland and struggling with debt. For more than a decade, we’ve helped over [volume] people. Don’t just take our word for it check out our Trustpilot reviews where we currently have a rating of 5/5. Thousands of the people we have helped left us a positive Trust Deed review. If you think you may not qualify for a Trust Deed, we can talk you through the other options available to you. We will always give you advice suited to you, with your best interests at heart. It is our mission to help you get out of debt rather than sell you a solution. If you want to start the journey to a brighter future, or just want a friendly chat and some advice give our experienced team of debt advisers a call. Or, you can try our Trust Deed Wizard tool to find out if you’re eligible. Whilst not a Trust Deed Forum, our Trust Deed Scotland WhatsApp service can be used to quickly find an answer to your question.Yorkhill Children’s Charity
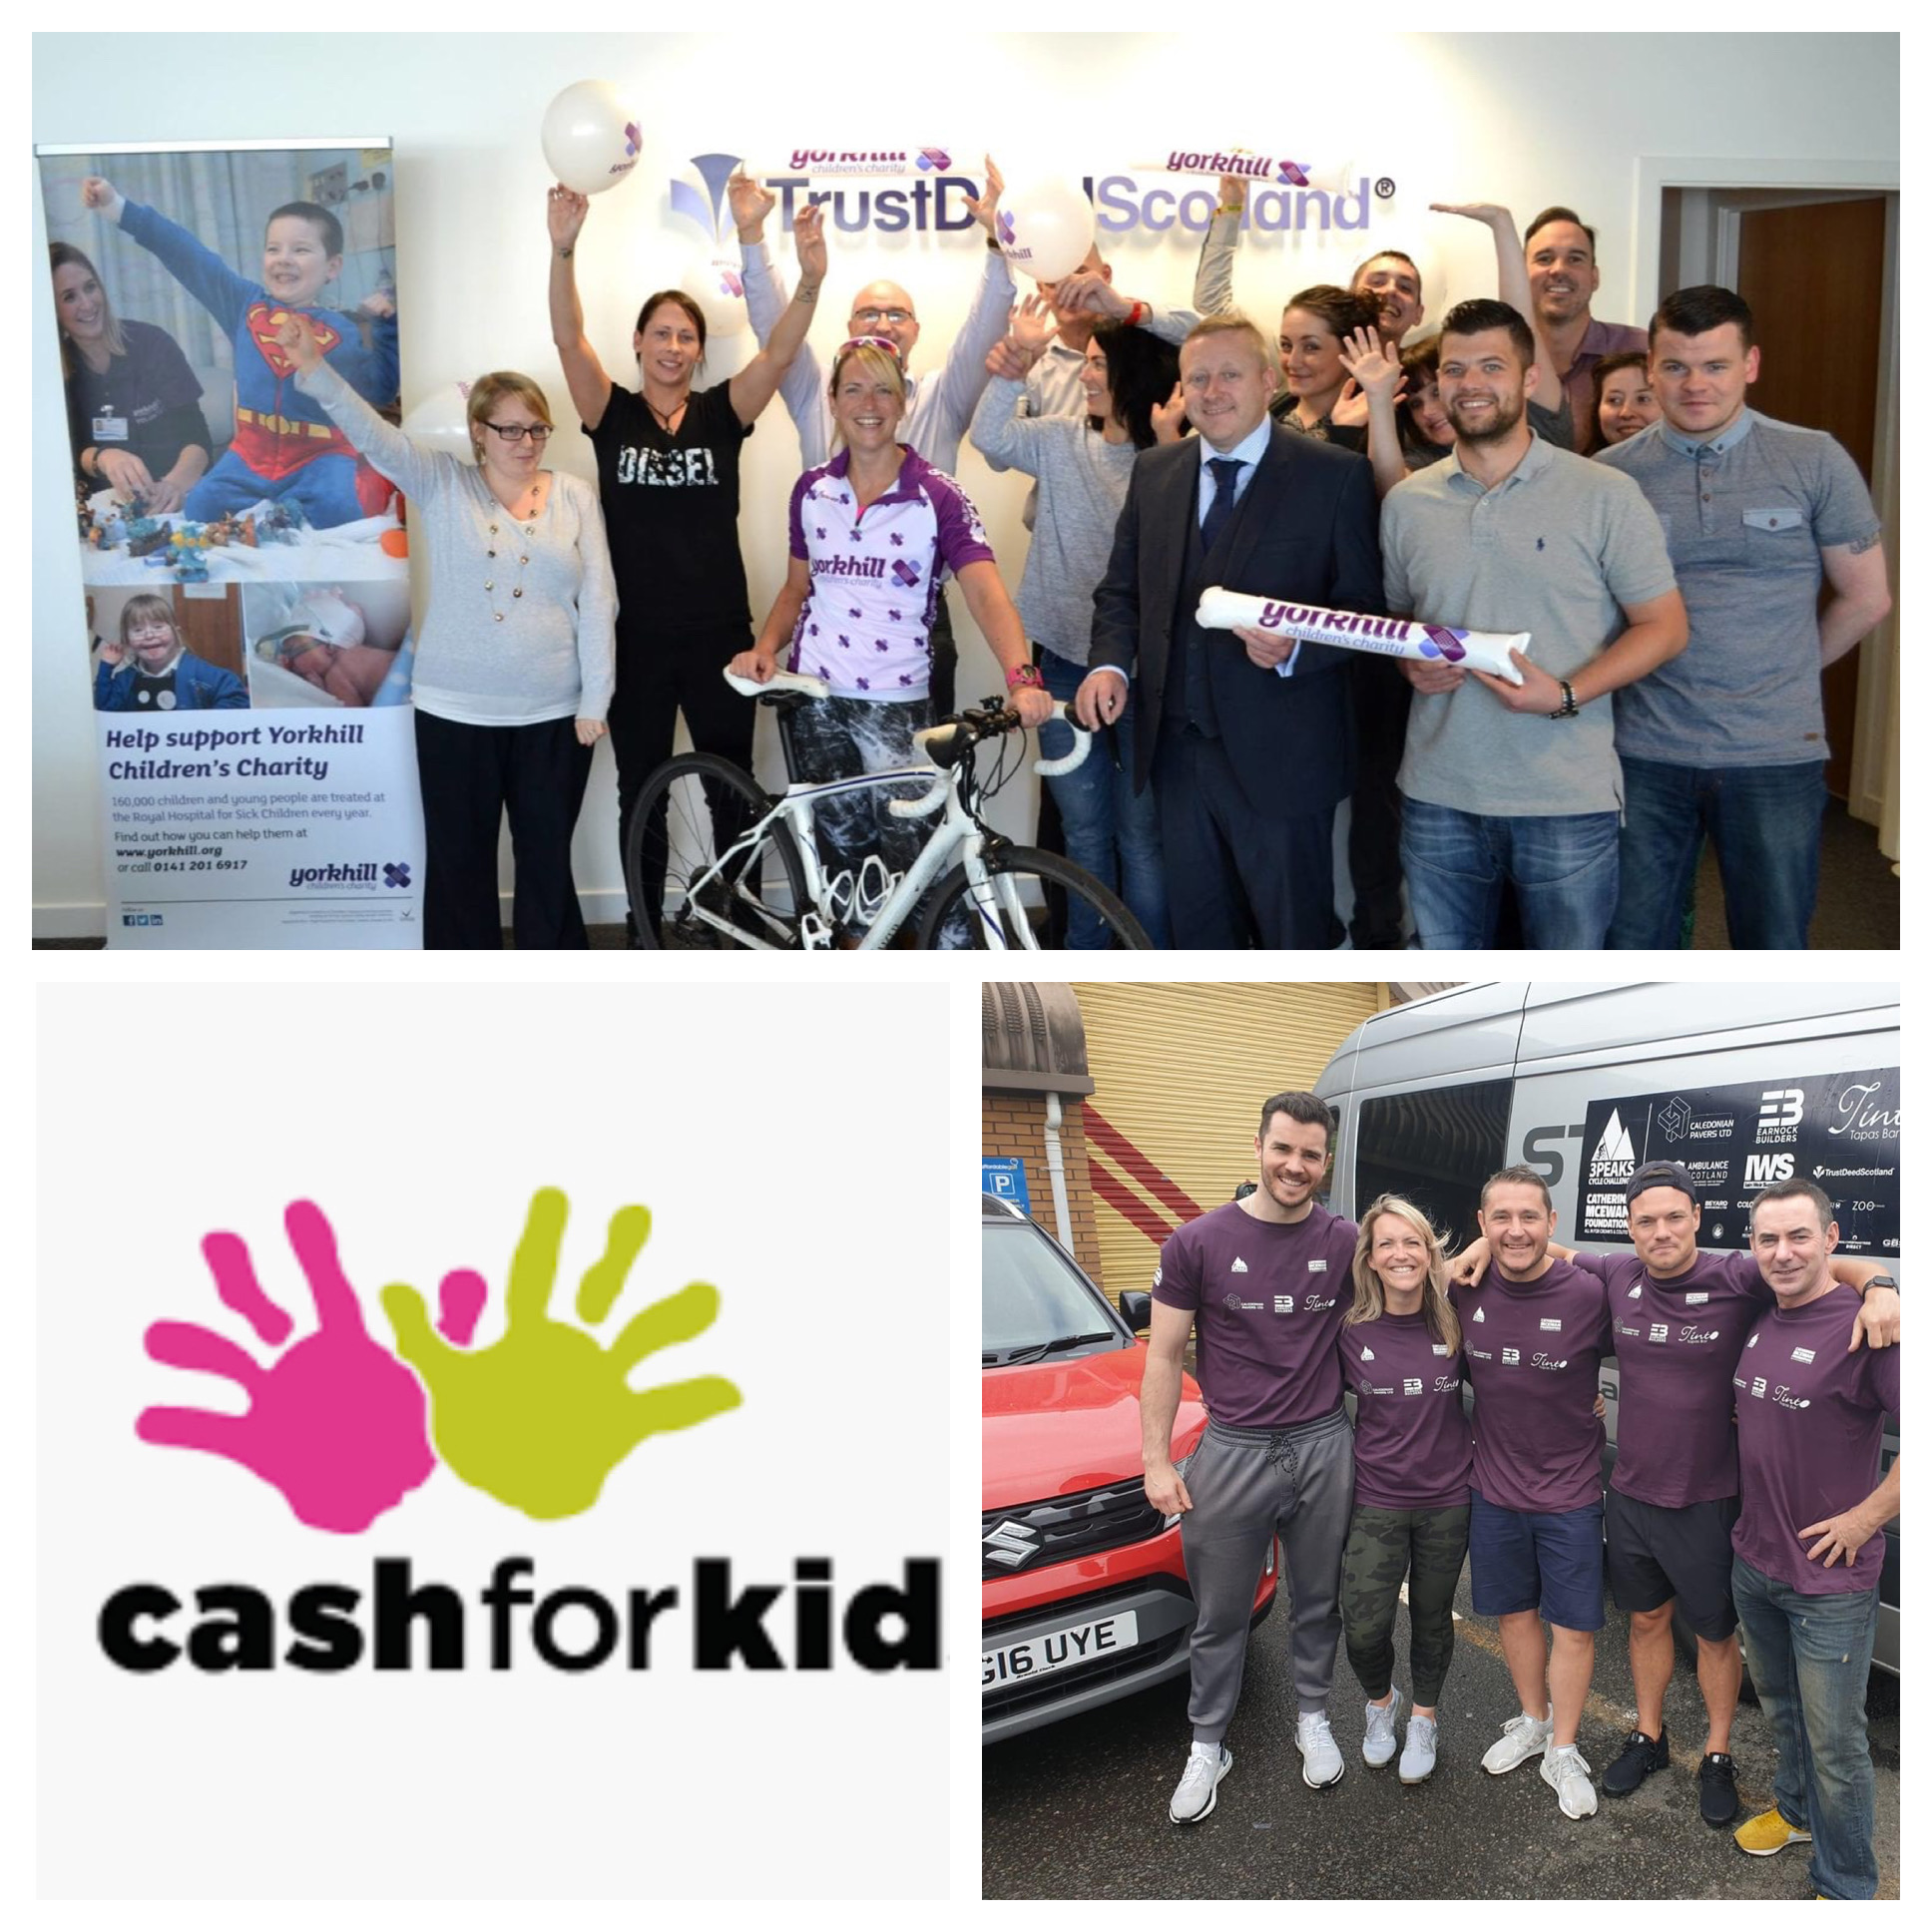
Trust Deed Scotland advisor, Lorna Carson, departs on the Sunday 23rd of August 2015 with five others for a mammoth undertaking in aid of Yorkhill Glasgow Children’s Charity. Cycling from London to Barcelona, (665km/1040 miles), in just ten days, they aim to raise £24,000 for the charity. The Trust Deed Scotland team had a bake sale in our office to help her reach her target.
Yorkhill Glasgow Children’s Charity raises money for the Royal Hospital for Children which treat 160,000 children every year.
The funds raised by the Glasgow based-charity, amongst other things, go towards medical equipment, family support and hiring some of the most skilled medical professionals in the industry.
One of our staff members who has first-hand experience of the Royal Hospital for Children said,
“The staff and doctors at Yorkhill Glasgow Children’s Hospital helped me through a tremendously difficult period when both of my children were ill at different points in my life. One of my daughters was diagnosed with an extremely rare bone disease after years of doctor’s visits with no diagnosis.
The other suffered and almost died from pneumonia when she was barely seven months old. I think if it wasn’t for the extreme professionalism of the doctors and nurses at Yorkhill, I may well not have my daughter today. The doctors and nurses sometimes go unrecognised and charities and fundraisers like this bring them to the forefront of everybody’s mind.”
Our bake sale attracted the other companies in the building, who gave generously in return for their fill of the many cakes our enthusiastic home bakers had prepared.
Once we counted the proceeds, we were very pleased to discover we had raised a fantastic £1,066.53!
After all the excitement was over and no one could possibly manage another mouthful, we were left with several boxes of cakes and biscuits. One of the company directors and a staff member took the goodies down to the Glasgow City Mission, a charitable organisation in Glasgow that helps vulnerable, homeless or poverty-stricken people and provides dinner to an average of 160 people each night. They sent us a lovely thank you letter on behalf of the homeless residents who enjoyed the cakes with their dinner.
The thank you letter the Glasgow City Mission sent Trust Deed Scotland.
If you would like to give something to the community, support Lorna’s cycle challenge and the fantastic Yorkhill Children’s Charity, please visit the team’s Just Giving fundraising page.
You can keep up to date with the Trust Deed Scotland foundation and all our fundraising efforts by following us on our official Trust Deed Scotland social media channels:
Get Your Finances On Track – 9 Tips In 2024
Get Your Finances On Track
When attempting to get your finances on track in Scotland, there is a range of Scottish debt solutions available to you but the first step is to try budgeting to reduce your debts and sort out your finances. There are simple tricks you can try to get the most from your income and minimise your monthly expenditure. It’s time to wipe the slate clean and regain control of your finances.1. Work out a budget
Everyone has to work on a budget, no matter how high their income or they’ll find they are living outside their means before too long. Write down a list of your monthly income after tax and anything else you receive such as working tax credits or private pension etc. Add up your total monthly income. Next, write down all your outgoings. Start with the priority bills: mortgage or rent and council tax. Then, write down all of your monthly direct debits. Finally, write down the amount you spend monthly on all other monthly expenses that aren’t included within your direct debits e.g. gas and electricity, food and housekeeping, fuel/public transport, parking costs, dentist/optician costs, house maintenance, pocket money and school trips etc. Add the totals up so you now have a final amount for your incomings and outgoings. Your income minus your outgoings is your expendable income. If you find you are spending more than you are earning and relying on overdrafts, credit cards or precious savings, you know you need to act immediately! Trust Deed Scotland may be able to help you get your finances back on track with a Protected Trust Deed. Try the Trust Deed Wizard to find out what you could expect to pay monthly.2. Cancel any unused memberships
When you went through your direct debits you may have come across something you had forgotten about and don’t use regularly. Did you have a gym membership that you forgot to cancel or are you paying for an online movie and TV watching account even though your partner has one and you can access it on multiple devices? Cancel anything you don’t want and don’t keep too many that you don’t need – it’s okay to have hobbies – you don’t have to limit your life too much.3. Switch tariffs/companies
You could save money by switching your bank, energy, mortgage, credit card, internet, TV package, mobile phone contract etc. to another tariff or company. Shop around to see what’s on offer, then call your current company and see if they can offer you the same. You’ve nothing to lose and it could save you in the long run. See our Trust Deed Scotland reviews page for thousands of testimonials written by people we’ve helped out of debt.4. Set up direct debits for recurring payments
Most companies have cheaper tariffs for customers who pay using direct debits, (this is particularly common with energy providers). Why pay more if you don’t have to? This way you also won’t run the risk of missing a payment and being charged a late fee.5. Be prepared
This sounds obvious but it takes some forward planning not to grab a quick coffee on the way to work or splash out in a sale on your lunch break. Take your own coffee and lunch with you. This simple change could be all the difference you need to see a change in your spending and the chances are it will be better for your health too! See our info hub article for 10 reasons people enter into a Trust Deed.6. Use a shopping list
Before going shopping for groceries, clothes or anything else, look at what you already have and then write a list of what you need to buy. This will prevent impulse shopping that will drain your wallet and leave you short for the month.7. Only buy what you can afford
This may sound like an obvious move too but a lot of people find themselves tempted by a sale in their favourite shop and put the balance on credit because they’ve found a ‘good deal’. Remember, if you end up paying more in the long run on interest, it was not a bargain. Use your expendable income on shopping and you’ll be less likely to build up debts and find yourself struggling with repayments. See our info hub article for 10 common questions about Trust Deeds.8. Sell Unwanted Items
You may be able to sell items you don’t want, need or use very often online or at a car boot sale. You might not get back what you paid for but something is more than the nothing you got from having it sitting in your house gathering dust!9. Consider Downsizing
Downsizing means selling or moving into a smaller, and typically cheaper, property. This could be a temporary measure and you could consider putting your goods into short-term storage.Get Your Finances On Track Today With Trust Deed Scotland
For tailored debt advice, Contact Trust Deed Scotland to see how we could help you get your finances back on track or view our Debt Advice Scotland guidance.How Trust Deeds Affects Credit Ratings
How Trust Deeds affect Credit Ratings
Trust Deeds help thousands of people each year get out of debt but there are pros and cons to every debt solution. The downside of a Trust Deed is the fact it negatively impacts your credit score. Although this sounds off-putting, it is important to consider all relevant factors before making a decision. There is a strong chance your credit may already have been affected if you have found yourself in the financial position where a Trust Deed would greatly improve your circumstances.
Have you ever missed a payment to one of your creditors?
If so, that missed payment will show on your credit file for six years, the same as a Scottish Trust Deed.
It is in your best interest to get out of debt sooner, rather than later. Entering a Trust Deed would affect your credit for the next six years but then your debts would be written off and you would able to rebuild your credit history from scratch. If you stay in debt and continue to default, without entering a debt solution such as a Trust Deed, your credit will got get the chance to improve until six years after your last default. This could prove to be a much longer time than if you’d entered into a Trust Deed.
If you’ve found yourself missing payments to your creditors or are reaching the stage where you can’t meet your payments, a Trust Deed may be the solution for you. Try the Trust Deed Wizard to find out how much you could expect to pay each month.
What exactly is a credit rating?
Your credit rating is determined using a mathematical equation that considers your credit history and determines how much of a risk you pose to lenders.
Generally, the higher your credit score, the more likely you are to be considered for credit.
What factors are likely to have a negative impact on your credit score?
- Any late payments or defaults.
- If you aren’t registered on the electoral role at your address.
- If you haven’t had much credit in the past, (your score is determined by past behaviour and it’s hard to decide whether or not you are reliable if you’ve not past credit to judge by).
- If you always pay off credit cards in full each month, (credit card companies make money by you being in debt. If you make the minimum payment each month and never default but do not clear your card, you are running up interest and are a better investment than someone who clears their card every month and doesn’t make the company much money).
- If you’ve applied for lots of credit in a short period of time.
- If you have a large amount of debt outstanding and/or are near your credit limits.
- If a lot of credit checks have been performed on you in a short period of time.
- If you have ever been Sequestrated or have any decrees, IVAs or any other court debt orders against you.
-
- Don’t make too many applications at once. Spread them out and try a credit card with as low interest as possible.
- Use the card monthly to make small purchases and clear them in full, to avoid your finances getting out of control again.
- Double-check you are on the electoral role.
- View your credit report to make sure it is accurate. If there are any inaccuracies, you can ask for these to be rectified, (speak to the company who put the entry on your credit file and if they will not remove it, go to the Information Commissioner’s Office and ask them to investigate on your behalf).
- Be careful not to take out any joint finances with someone else with poor credit, (such as joint mortgages and loans), as this may affect your credit further.
- If there’s anything relevant you’d like to say about something on your credit history, (for example, perhaps you missed a payment due to redundancy or hospitalisation), you can ask to add a notice of correction which anyone checking your credit history would see. This does not guarantee the person checking would take this into account but depending on the situation, this could make a difference as the credit history only shows dates and figures, not reasons for missed payments.
10 Common Trust Deeds Questions
We often receive calls at Trust Deed Scotland from people asking questions about Trust Deeds.
We’ve compiled a list of some of the most commonly asked questions so that you can learn more about the process.