What is a DAS?

What is a DAS? DAS stands for Debt Arrangement Scheme and is a statutory debt solution with many of the same benefits as a Trust Deed. The Debt Arrangement Scheme lets you apply for a Debt Payment Programme (DPP) which helps you repay your debts in full by making affordable monthly payments. Interest and charges are frozen from the date of your application being made. The Debt Arrangement Scheme is only available to people living in Scotland, and there is no equivalent solution for the rest of the UK – however, a shorter term solution is called the ‘Debt Respite Scheme (Breathing Space) ‘ and was introduced in May 2021. This is more similar to a Statutory Moratorium in Scotland. The Debt Respite Scheme offers people in the rest of the UK a period of 60 days respite from their creditors. The Debt Arrangement Scheme was first introduced in 2004 to help Scottish residents stay in control of escalating debt without having to follow insolvency procedures.

Who is eligible for a DAS?

To be eligible for a DAS, you would typically meet the following basic criteria:
  • Have one or more debts
  • Not be subject to sequestration or any other insolvency procedure
  • Have a reasonable amount of surplus income after paying priority bills and household expenses
  • Be resident in Scotland
There is no set minimum level of debt you need to have in order to be eligible for the DAS, however, this solution is designed for people who are unable to manage their current debt repayments. All unsecured debts can be covered by a DAS, for example: Credit and store cards, personal loans, overdrafts and catalogue debts. You can also include mortgage, secured loan and rent arrears (but not ongoing payments). A few debts cannot be included in a DAS Scotland including fines imposed by any court and any liability due to fraud. In order to work out whether a DAS is worth applying for, we would always recommend that you speak to an experienced debt advisor and work out the pros and cons, after establishing what your situation looks like based on your affordability, lifestyle and needs.

What is a DPP?

The term DPP stands for Debt Payment Programme – this is the repayment plan agreed between you and your creditors under the terms of the Debt Arrangement Scheme. Your Debt Payment Programme is arranged by a qualified money advisor, who will help you to propose an acceptable repayment plan to your creditors, set at an affordable level, based on your circumstances. Although at the time of your application, interest and charges on your debts are frozen under DAS – you will be required to pay back what you owe in full.  

What are the benefits of a DAS?

  • Only pay what you can afford
  • Freezes interest and charges
  • Protects your home and car
  • Reduces creditor contact
  • Monthly payments can be adjusted if your circumstances change
  • DAS can stop earnings arrestments
  • You can take payment breaks from a DAS if required
  • Joint DAS applications can be made by couples/spouses who live together
  • DAS does not involve court proceedings
  • If creditors do not accept the proposal but are owed up to 10% of the total debt, then the DPP will be automatically approved
  • Creditors that do not accept the proposals and are owed more than 10% of the total debt can be forced to comply with the arrangement if it is judged to be “fair and reasonable” by the DAS Administrator
  • The payment made does not have to offer the full disposable income, a reduced amount can be offered to allow the individual more affordability for their general living expenses

What are the risks of a DAS?

  • You must repay the full amount that you owe, no debt is written off
  • If you do not keep up with your DPP payments, your DAS can be revoked
  • DAS will have a negative effect on your credit rating
  • Once in a DPP, your details will appear on the public DAS register for the plan’s duration
  • You will not usually be able to access further credit whilst in a DPP
  • A DPP may be rejected by creditors and deemed not ‘fair and reasonable’ by the DAS Administrator

What are the alternative solutions to a DAS?

A DAS is designed to help you pay back your debt at regular, manageable intervals – without the threat of legal action hanging over you, they can also be used by individuals and businesses who are struggling with unaffordable debts. However, that doesn’t mean that the Debt Arrangement Scheme is right for you. On some occasions, a Scottish Trust Deed may prove to be a more fitting solution for you, depending on your circumstances. Trust Deeds may allow you to write off some of your unaffordable debt in a quicker timescale. However, your assets such as your home require more scrutiny in order to establish your eligibility to potentially qualify for a Scottish Trust Deed. Full Administration Sequestration or Minimal Asset Process Sequestration are two other formal solutions to debt, while you may also consider informal solutions such as equity release, or a debt consolidation loan. In any case, our advice is always to talk about your situation with an experienced debt advisor, who can not only explain what is a DAS, its advantages and disadvantages, but also give you tailored debt advice on all available alternative solutions to a DAS.

Who can set up my DPP?

Trust Deed Scotland® are experienced debt advisers and provide tailored debt advice on all available debt solutions in Scotland. We make sure that our clients get personalised debt advice based on their affordability, lifestyle and needs. If you are struggling with your monthly debt repayments but feel that you could repay what you owe in full, given sufficient time to do so, then the Debt Arrangement Scheme may be a good option for you. Find out how long it takes to set up DAS and get started now by trying our online form, or by calling us on 0141 221 0999.

Scottish Trust Deed: What happens next?

What happens next in the Scottish Trust Deed application process? If the individual decides that a Scottish Trust Deed is their best option to deal with their debts, then the paperwork will be signed and the Trustee will attempt to have the Trust Deed protected. Protection is achieved in the following way: • The Trustee places a Notice in the Register of Insolvencies (ROI). • No later than 1 week from publication of the Notice, the Trustee will present a proposal to the creditors based on the individual’s assets and liabilities and the income and expenditure. • After a period of 5 weeks from publication of the Notice, if the Trustee has not received written objections from a majority in number of the creditors or any creditor(s) owed more than one third in value of the total debt, then the Trust Deed will be registered as protected. • The Trust Deed becomes protected from the date it is registered on the ROI by the Accountant in Bankruptcy (AiB). By obtaining protected status, this means that the creditors cannot take any further action against the individual for the recovery of their debts – they are legally bound by the terms of the Trust Deed. Once protected, the Trustee’s main duty is to realise the assets and/or collect regular contributions from the individual’s income, for a minimum period of 4 years, in order to make the agreed dividend payment to the creditors. The agreed contribution is subject to review at least annually or any time when an individual experiences a change in circumstances. It is essential that the individual co-operates fully with the Trustee for the duration of the Trust Deed by providing all requested information, keeping the Trustee up to date with any changes to their income or expenditure, advise of any changes to their contact details and, as far as possible, maintaining the agreed payments. At the end of the Trust Deed, the individual will be discharged from all debts included in the Trust Deed and can hopefully look forward to life after debt

Scottish Trust Deed Case Studies

Scottish Trust Deed Scenario 1
  • Married couple with 2 children of school age, Mr & Mrs in full time employment, Mr earns £2,000/m, Mrs earns £1,200/m.
  • Mr has debts of £40K, Mrs has debts of £25K, £20K of the debts are joint, total repayments are £1,300/m.
  • Home is jointly owned with £5,000 of equity.
  • Jointly owned Term Life Assurance policy.
  • Motor vehicle on HP, Mr is the registered owner & uses the car for work purposes.
Debts were incurred for home improvements and then to supplement the household income when Mrs took time off work to look after their children before they started school, a large consolidation loan was obtained in an effort to reduce their monthly outgoings but they continued to utilise other credit and their level of debt spiralled out of control. They then sought financial advice. Solution: Both Mr and Mrs signed Trust Deeds; Mr pays £250/m, Mrs pays £150/m for a 4 year period; Mrs’s parents are paying 20 monthly payments of £250 to acquire the Trustee’s interest in the property – £2,500 to each Trust Deed; the premium for life assurance policy is an allowable expense; Mr has also been allowed the HP payment as an expense and the HP company is willing to allow the agreement to continue. At the end of the Scottish Trust Deed, creditors will have received a payment of approx. 20p in the £ from Mr and a payment of approx. 17p in the £ from Mrs, all remaining debts will be written off. The joint debts will receive approx. 37p in the £ in total from both Scottish Trust Deeds. Scottish Trust Deed Scenario 2
  • Divorced male, self-employed tradesman, 1 dependant who lives with his ex-wife and for whom he has visitation rights, earns approx. £1,800/month.
  • Debts of £35,000, including £10K shortfall due to mortgage lender from repossessed family home and self-assessment tax debt of £8K.
  • Now lives in rented accommodation, family home was solely owned.
  • Works van, owned outright, poor condition, high mileage.
Debts were incurred in previous marriage to maintain his family’s standard of living, ex-wife was unemployed, loans and credit cards were used to supplement his income, marital breakdown followed and the family home was repossessed, he struggled to maintain his repayments but his income was insufficient to pay his daily living expenses, child maintenance, household bills and his creditors. He then sought financial advice. Solution: He signed a Trust Deed, paying £190/m for a 4 year period; the van will be kept as it is required for work purposes; an allowance has been made for child maintenance payments, ongoing self-assessment tax and NI contributions (he must pay his ongoing tax liabilities); the property shortfall will be treated in the same way as all other debts; at the end of the Trust Deed all creditors will have received a payment of 10p in the £, all remaining debts will be written off. Also see Debt Arrangement Scheme: What happens next.

Scottish Trust Deed Advice

You can get debt advice today by calling Trust Deed Scotland® on 0141 221 0999 or start your debt help journey by completing our Trust Deed Wizard® tool. Our experienced advisors give friendly, confidential and non-judgemental debt advice that covers the advantages and disadvantages of Scottish Trust Deeds and all other formal debt solutions open to Scottish residents.

Debt Arrangement Scheme: What happens next?

What happens next in the Debt Arrangement Scheme application process? If the individual chooses DAS, the individual commits to a debt payment programme (DPP) based on all their creditors receiving regular payments of their share of whatever the individual can reasonably afford each month. A DPP can last for any reasonable length of time (normally up to 10 years), depending on the amount of debt and how much the individual can pay. A DPP under DAS is proposed to creditors in the following way:
  • Proposals are sent to all the creditors and they have 21 days to respond if they wish to object to them.
  • If no creditors object, then the DPP is approved automatically.
  • If creditor(s) object and they are owed up to 10% of the total debt, then the DPP application will be automatically approved.
  • If one or more creditors object and they are owed more than 10% of the total debt, then the DPP can still be approved if it is judged to be “fair and reasonable” by the DAS Administrator (Accountant in Bankruptcy).
  • It is possible that the circumstances may change whilst the individual is repaying the debts under DAS, in which case the DPP may be varied to accommodate this change without penalty.
  • The continuing money adviser will help the individual produce an alternative debt payment programme based on the current situation and send this for approval.
  • The same 10% rule (described above) applies for approval of variations to already approved DPPs
  • So long as the amended proposal is fair, the creditors will not be able to stop the debt payment programme being approved.
  • If the DPP is refused, the individual has the right to appeal against the decision. However, the individual may need to look at other options, such as a Protected Trust Deed or Sequestration.
Only qualified money advisers can advise on and manage a DPP under DAS. A money adviser can be employed in the free advice sector, such as with the local Citizens Advice Bureau or local authority money advice team or the Money Adviser can be an insolvency practitioner (or a suitably qualified member of his/her staff). Once the DPP is approved, the individual only has one affordable payment to make, therefore, their monthly outgoings should be drastically reduced and the pressure from creditors should stop.

How much does a DAS cost?

There are no fees payable by an individual entering into the DAS. This is the same for all individuals whether they use a private sector firm (e.g. Harper McDermott Ltd) or a public sector organisation (e.g. CAB or local authority Money Adviser). The costs of administering the scheme are borne by the creditors i.e. from every £ received into the scheme, 22p is used to pay for the costs; this 22p is paid to the DAS Administrator (2p) and the Money Adviser (20p). The remaining amounts are distributed amongst all creditors on a pro rata basis and a successfully completed DPP deems all debts to be repaid in full.

Debt Arrangement Scheme Case Studies

Debt Arrangement Scheme Scenario 1 Married Couple, with 2 young children. Mr is in full time employment and Mrs is unemployed. Mr has credit card debts totalling £7k, Mrs has debts of £4k and there is £5k of joint council tax arrears (i.e. total household debts of £16k) They had been paying minimum payments on their debts, totalling around £300 per month, which was just affordable but due to high interest rates the outstanding balances were reducing very slowly. Unfortunately, Mr’s wages were then arrested for non-payment of council tax. As a result of this, they could afford only £150 per month for all their other debts, and they fell into arrears. Mr & Mrs Y set up a joint DAS. As the earnings arrestment is lifted upon approval, they can afford to pay £300pm. All further interest and charges are frozen and their debts will be repaid in full in around 4.5 years. Debt Arrangement Scheme Scenario 2 Single man in full-time employment. Owns home worth £140k, with outstanding mortgage £80k. Owns car worth around £7k. Did not wish to lose car or sell his home as has elderly parents living nearby, who require help getting around. Had unsecured debts totalling £25,000 due to previous business failure. He could afford to pay £350 pm to his unsecured debts and attempted to set up a payment arrangement with his creditors on this basis through a Debt Management Company. Unfortunately, one former business supplier is owed £8k and is not willing to agree to any payment proposals via the informal DMP, insisting that the individual must pay the full debt or face legal action. The creditor is aware of the equity in the house and the debtor fears that this creditor may eventually seek to have him made bankrupt and force a sale of his home. He has tried to re-mortgage to release funds but was rejected. Solution: Application for a DPP under DAS is made, paying £350pm to his creditors. This means his debts will be fully repaid within 6yrs and his home and car will remain protected. The difficult creditor objected to the proposals, but they were deemed “fair and reasonable” by the DAS Administrator. This means that the creditor was forced to accept the arrangement and is no longer able to take any enforcement action as long as the individual successfully completes his DPP. Also see Scottish Trust Deed: What happens next.

Debt Arrangement Scheme Advice

You can get debt advice today by calling Trust Deed Scotland® on 0141 221 0999 or by completing our Trust Deed Wizard® form. Our experienced advisors give friendly, confidential and non-judgemental debt advice that covers the advantages and disadvantages of Scottish Trust Deeds and all other formal debt solutions open to Scottish residents.

Low And Grow DAS

As the country continued to cope in the wake of the Covid pandemic, many people needed to deal with the impact of debt. The Debt Arrangement Scheme (DAS) is a formal debt solution in Scotland that has seen significant growth in the last decade Such has the growth in the use of the Debt Arrangement Scheme been in Scotland, that the number of people using the solution grew 18% in 2020 against 2019, according to official Scottish government statistics. Under existing affordability rules, the solution can only be put in place if an individual has the ability to be able to make regular repayments from their income. From 11 January 2021, it was possible for those struggling with unmanageable debt as a result of a loss of income due to the pandemic, to make minimum or token payments through DAS with a view to increasing them when their income returned to a normal level.

What was a Low and Grow DAS?

Low and Grow Debt Payment Plans, or Low and Grow DAS as they are also referred to, were a tool developed during Covid times to help people with unaffordable debts in Scotland. For many Scottish residents, they provided vital breathing space and a welcome opportunity to take control of household finances. The first few months of the year are typically the time of year when more people need help with their unaffordable debts. UK government figures showed that after the first lockdown, over 700,000 Scots had been furloughed under the UK job retention scheme “furlough” with many households struggling with debt, the then-created Low and Grow debt payment plan was intended to welcome relief to those who are in a position to repay their debt over a longer period of time but require a short term solution in the intermediate period before their regular income returns to normal. When a person repays their debts through DAS, interest and contractual charges are frozen. DAS lifts wage arrestments; stops court action including Sequestration (bankruptcy in Scotland) and requires one monthly payment that is distributed to all creditors on their behalf. You can find out more the advantages and disadvantages of the Debt Arrangement Scheme and alternative formal solutions such as Trust Deeds by calling Trust Deed Scotland on 0141 221 0999. Jamie Hepburn, Minister for Business, Fair Work and Skills said at the time: “I am acutely aware of the impact that the pandemic and necessary restrictions are having on household finances. In this uncertain time, I would encourage anyone experiencing problems with debt to seek advice as soon as they can. “DAS is an enormously valuable tool to help manage problem debt and the Scottish Government has worked closely with the advice sector and other stakeholders to introduce greater flexibility in the operation of the scheme to assist those impacted by the pandemic.” Speaking back in 2021, Trust Deed Scotland® said: “Getting early, tailored debt advice remains crucial as the country continues to cope with the pandemic. Every day we speak to people who are feeling overwhelmed by the challenges of lockdown, homeschooling, poor mental health, caring for elderly relatives, reduced income and many are feeling overwhelmed with their debt. Many of those individuals have had a sudden change in their circumstances and are prevented from repaying their debts due to a short term inability to make repayments. That short term problem can sometimes lead to a situation where the person can never catch up and a debt solution is required. We welcome the newly created Low and Grow debt payment plan and urge people struggling with problem debt to seek debt help now.”

Debt Payment Programmes under the Debt Arrangement Scheme vs. Minimal Asset Process

Minimal Asset Process (MAP) is a route into Sequestration (bankruptcy) aimed at individuals who have no, or little assets and who also have little, or no income. DAS is not insolvency, it is the only statutory debt management plan in the UK. In order to find out which option suits an individual better, it is essential to seek advice before making a decision. Both solutions, in addition to Trust Deeds, are effective ways of formally dealing with unaffordable debts. While it’s true that many people currently furloughed, or claiming Universal Credit may loosely qualify for both, a clear understanding of your personal circumstances, assets, future ability to repay debts, and/or desire to rebuild a credit rating need to be correctly assessed. Bankruptcy has always carried the greatest stigma and many people that we’ve spoken to over the years have struggled on for years to avoid being made bankrupt but the reality is that in the right situation, the Minimal Asset Process route and Full Administration Sequestration are effective tools that have helped thousands of people rebuild their lives through the years.

DAS or MAP

If you are struggling to repay your debt and feel that MAP is too severe, or a formal debt solution like DAS, Trust Deeds doesn’t seem like an arrangement that you want to consider, there are other tools that you can explore in the short term, including a Statutory Moratorium.

Statutory Moratorium Scotland

If you are worried that you may be at risk of Sheriff Officers taking action against you, a Statutory Moratorium (Scotland) is a legal instrument that you can use to protect yourself. Statutory Moratoriums also protect you from creditors making an application for you to be Sequestrated. The Statutory Moratorium gives you 6 months of protection from a Sheriff Officer taking action against you, such as arresting your bank account or freezing your income. If you are worried a Sheriff Officer may freeze your bank accounts, or arrest your wages, then a Statutory Moratorium may be suitable for you. It can also stop possessions like cars, or any other valued asset item, being attached. The process is designed to allow breathing space for anyone struggling with their debts, so they can consider their options, regardless of whether those options are the Debt Arrangement Scheme, a Trust Deed or Bankruptcy (Sequestration). Essentially, a Statutory Moratorium can be used to buy you time, until the pandemic is over so that you can review your options at a later date when you have more information on your future ability to pay. However, bear in mind that a Statutory Moratorium is not a long-term solution.

Payment Breaks and Tailored Support

You may be able to apply for payment breaks directly with your lenders, at their discretion. This will generally give you three months of payment breaks per application, this process becomes known as Tailored Support. Tailored Support apply to a range of products from credit cards and loans to mortgages and car finances. Applying for a payment break under tailored support will most likely impact your credit rating to some extent. As Tailored Support is more ambiguous in its definition, it’s down to your lender to advise on what they can offer you including a (further) payment deferral a (further) period of reduced payments, waiving or reducing interest, agreeing on a repayment plan and/or refinancing your credit agreement.

Advice on your options

To find out more about managing your money and getting free advice, visit Money Helper, an independent service set up to help people manage their money. Trust Deed Scotland® can give you advice on DAS but also advice on applying for a Statutory Moratorium and our experienced team, offer debt advice that is…
  • Non-Judgemental – Our friendly, helpful team want to help find a solution that suits your needs.
  • Confidential – We do not share your details with any other companies. Your data is safe and secure.
  • Experienced – [volume] people helped and over [reviews] five-star reviews on Trustpilot.
  • Tailored – Pros and cons of all formal solutions explained.

Apply for a formal debt solution

You can find out more about applying for a formal debt solution by using our online form, or by calling us on 0141 221 0999. Our experienced debt advisors provide tailored debt advice outlining the risks and benefits of the Debt Arrangement Scheme and other formal Scottish debt solutions including Protected Trust Deeds and Sequestration.
Demand for debt advice to increase by up to 60% in 2021

The Money and Pensions Service expects the demand for debt advice to increase by up to 60% by the end of 2021 and this is likely to lead to an increase in the need for debt relief. In August 2020 Citizens Advice estimated that 6 million UK adults have fallen behind on at least one household bill during the pandemic, with 20% of those who have fallen behind on their bills unable to afford household essentials. An estimated 3,000,000 more people than before the pandemic will need support with problem debt by the end of 2021. As a result, proposals have been outlined by the UK government to increase the financial eligibility criteria for Debt Relief Orders (DROs) – the English, Welsh and North Irish equivalent of the Scottish Minimal Asset Process route to bankruptcy. (MAP) A DRO/MAP is a route into bankruptcy (Sequestration in Scotland) for people who have problem debt and who also have a low income, with little or no assets. The aim of the proposed changes is to help more people deal with financial difficulties and to achieve a fresh start. The UK government is publicly consulting on changing the eligibility criteria to enter into a DRO to:
  • Increase the total amount of debt allowable to £30,000 (from £20,000)
  • Increase the value of assets owned by the individual to £2,000 (from £1,000)
  • Increase the level of surplus income to £100 (from £50) per month
NOTE: For more information on how the Minimal Asset Process route to Sequestration works, please read our MAP guide. Kwasi Kwarteng, Business Secretary said: “Suffering from financial difficulties places a huge amount of stress on people’s mental health and wellbeing, which is why we are committed to giving more people who are struggling with debt a chance for a fresh start. Debt Relief Orders are a valuable tool for supporting vulnerable people to get to grips with their problem debts. Our plans to increase the eligibility criteria will mean many thousands more could benefit from this help.” Trust Deed Scotland® further advised: “Many people in the rest of the UK stand to benefit from the proposed changes, at a time when they are most needed, especially as it’s likely that the additional £20 per week payment made available via Universal Credit will be discontinued. In Scotland, thanks to changes already passed as part of the Coronavirus Bill in 2020, MAP application fees had already been reduced or waived for people with the lowest incomes and the qualifying debt ceiling limit has also increased. However, thanks to additional Statutory Moratorium support that was also passed as legislation in 2020, and more recently, we now also have the option to offer a Low and Grow payment plans in Scotland. Find out more about What is a Statutory Moratorium. The Low and Grow DAS process allow individuals to make minimum or token payments through DAS with a view to increasing them when their income returns to a normal level. We are hopeful that for people struggling with debt throughout the rest of the UK, they too can benefit from the proposed changes should Payment Breaks and Tailored Support offered by creditors not be enough to resolve their finances difficulties.” If you are experiencing financial difficulties and are also affected by a drop in your regular income, you can find out more about your options including Statutory Moratoriums, MAP and Low and Grow DAS by calling our advice team on 0141 221 0999. Alternatively, if you are experiencing financial difficulties but continue to receive a regular income, you can find out more about Trust Deeds, and the Debt Arrangement Scheme which allows you to manage your unaffordable debt by significantly reducing your monthly creditor payment obligations, freezing your interest and charges and reducing creditor contact.

Can I apply for MAP?

To apply for Minimal Asset Process Sequestration, you must meet the following conditions:
  • You must owe a total debt of at least £1,500.
  • You must not owe more than £25,000 (This may / may not revert back to £17,000 after March 31 2021).
  • You do not own a single asset worth over £1,000 (this excludes a vehicle which does not exceed £3,000 and is reasonably required).
  • The total value of assets does not exceed £2,000.
  • You must have received advice from an Approved Money Adviser.
  • You must be living in Scotland or have lived in Scotland within the last 12 months.
  • You must not have been made bankrupt in the last five years.
  • You must not have been made bankrupt through the Minimal Asset Process within the last 10 years.
  • You must pay the reduced application fee of £50 to the AiB (This may / may not continue to be reduced/waived after March 31 2021).
  • You must have a certificate for sequestration signed by an authorised person
  • You must have been in receipt of benefits only, for the last six months; or
  • A money adviser has assessed your income and expenditure using the common financial tool and you have no surplus to pay a debtor’s contribution.
  • You do not own any land or property.

About Trust Deed Scotland®

Our experienced debt advice team have helped over [volume] people in Scotland get their finances back on track. As well as advice on MAP, we offer formal Scottish debt solutions such as Protected Trust Deeds and the Debt Arrangement Scheme. With over [reviews] 5/5 reviews, we’re rated No.1 in Trustpilot’s debt relief service category. Call us on 0141 221 0999 for friendly, non-judgemental debt advice or complete our Trust Deed Wizard tool today.  

Council Tax Arrears Statistics Released by Citizens Advice

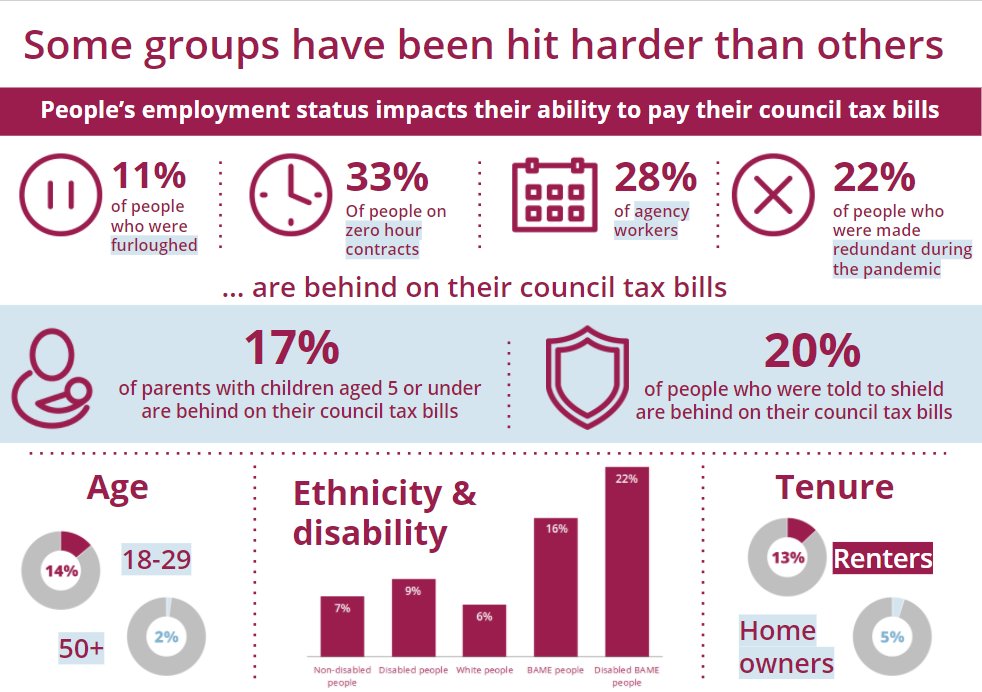
Over 3,500,000 people in the UK now have council tax arrears debt, with an average of £800 council tax arrears, reports Citizens Advice* Founded in 1939, Citizens Advice is a network of 316 independent charities throughout the UK guided by four principles: A free service, Confidentiality, Impartiality and Independence. The unavoidable debt report published by Benedict Guindi and Tilly Cook of Citizens Advice said that the pandemic and the restrictions put in place to control it, have had a dramatic impact on household finances with many people have been made redundant, furloughed, become too ill to work or have taken time off to care for a loved one. Some groups identified as being most affected by council tax arrears included:
  • 11% of people who were furloughed
  • 33% of people on zero-hour contracts
  • 28% of agency workers
  • 22% of people who were made redundant during the pandemic
  • 16% of people of BAME
  • 22% of people of BAME and with a disability.
  • 17% of parents with children aged 5 or under are behind with council tax arrears debt
  • 20% of people who were told to shield are behind with council tax arrears debt.
  • 14% of people aged 18-29 are behind on their council tax
  • 13% of renters and 5% of homeowners indicated that they had accumulated council tax arrears debt.
As a result of the findings of their data, Citizens Advice said: “On average, the people we help with council tax debt have just £20 left after covering essential living costs to pay off debts. 40% have a negative budget, meaning their income doesn’t cover their living costs. People are often forced to make trade offs between repaying their debts and covering essential living costs. During the pandemic, 17% of people with council tax arrears were unable to afford food in comparison to 3% of the total population.” “Councils should prioritise writing off the debts of those who are struggling the most financially, such as those in receipt of Local Council Tax Support and people receiving benefits. There were existing problems with the way council tax is collected before the pandemic hit. The way the regulations are designed makes it harder for people with council tax arrears to arrange and make repayments. The Ministry for Housing, Communities and Local Government should use secondary legislation to amend the Council Tax (Administration and Enforcement) regulations to:
  • Stop people being liable for their entire annual bill if they miss 1 monthly payment.
  • Make it easier for councils to improve collection by giving them more powers to collect debt in a fair way without getting a liability order first.
  • Set out more steps councils must take before using the court process.
This would ensure that all people in debt are given the option of affordable repayments to get back on track.”
Citizens Advice - Council Tax Arrears Stats
The infographic image above was taken from Citizens Advice unavoidable debt report and remains © of Citizens Advice.

Council Tax Arrears Debt in Scotland

As reported in the Glasgow Herald in early January, Citizens Advice Scotland warned of a potential Council Tax explosion, with CAS financial health spokesman Myles Fitt saying: “Scotland is potentially facing an explosion of council tax debt in 2021. The figures before the pandemic are bad enough, but the real fear is that Covid-19 is going to make matters much worse. Councils across Scotland showed a real empathetic approach to those who found themselves in council tax payment difficulties, and the payment breaks in the first six months of the pandemic were extremely welcome. However, this has led to arrears building up, arrears that will be difficult to meet for the many people who have during that period experienced an income drop due to unemployment or reduced working hours. “For others, this problem is yet to come in 2021 when the economic squeeze on personal finances is felt as the furlough scheme and payment support measures close at the end of April, ironically in the same month the first payments of council tax in the new financial year are due.” CAS is calling on people to make use of the Scottish Government’s council tax reduction scheme which can help reduce future payments. For some people, it can also offer a backdate of up to six months. Contact your local authority for more information. All local authorities should have information on their website including: Glasgow council Edinburgh council Aberdeen city council North Lanarkshire council South Lanarkshire council Highland council East Ayrshire council North Ayrshire council South Ayrshire council Trust Deed Scotland® said “Falling behind on priority debts such as council tax can have the severest of consequences. Council tax arrears enforcement action can escalate quickly when there is non-payment of council tax with Sheriff Officers being used to collect outstanding council tax arrears debt with enforcement action such as wage arrestments being used as a last resort to collect outstanding monies. We’re thankful that Citizens Advice have highlighted these groups that they have identified as being most at risk of developing problems with their council tax and we offer tailored debt advice to anyone who is struggling with unaffordable debts, whether they have council tax arrears debt or other types of unsecured debts such as credit cards and loans. As well as being able to provide formal, statutory solutions such as Protected Trust Deeds and the Debt Arrangement Scheme, we can also provide some breathing space for our clients who need more time to think about the best solution for their problem debt by using a Statutory Moratorium.”

Help with unaffordable debt in Scotland

To find out more about managing your money and getting free advice, visit Money Helper, an independent service set up to help people manage their money. Citizens Advice Scotland (0800 028 1456) can give you free, impartial debt advice alongside other money charities including National Debtline (0808 808 4000). As well as formal debt solutions, The Trust Deed Scotland® team offer debt advice that is… Non-Judgemental – Our friendly, helpful team want to help find a solution that suits your needs. Confidential – We do not share your details with any other companies. Your data is safe and secure. Experienced – [volume] people helped and over [reviews] five-star reviews on Trustpilot. Tailored – Advantages and disadvantages of all formal solutions explained. You can find out more about how we can help you by using our Trust Deed Wizard, or by calling us on 0141 221 0999. Our experienced debt advisers provide tailored debt advice outlining the pros and cons of the Debt Arrangement Scheme and other formal Scottish debt solutions including Protected Trust Deeds and Sequestration. *Citizens Advice commissioned ICM unlimited to conduct a survey of a representative sample of 6,004 adults living in the UK. The survey took place between 12th and 25th November. The sample has been weighted by age, gender, region, social grade, work status and ethnicity to be representative of the UK adult population. The 3.5 million in arrears figure is based of 7% of the population being behind on their council tax bills. Then extrapolating this out to the UK adult population of 52.5 million
Rent Arrears Debt Warning by Resolution Foundation

Almost half a million people across the UK have fallen behind on rent or mortgage payments as a result of the coronavirus pandemic, reports the Resolution Foundation. The Resolution Foundation is a UK think-tank that is focused on improving the living standards of those on low-to-middle incomes. Founded in 2005, the Foundation’s established work programme includes incomes and inequality; jobs, skills and pay; housing, wealth and debt; tax and welfare; public finances and the economy. The study into rent arrears found that as many as 450,000 out of an estimated 750,000 people in arrears on housing payments and reporting on the findings, Lindsay Judge a Senior Research and Policy Analyst who leads on housing, advised that many families had suffered ‘huge hits’ to their household earnings and that few have savings to fall back on. 300,000 people are thought to have dependent children. “To make matters worse, measures that could ease the pressure, such as discretionary housing payments from local authorities and negotiated rent reductions from landlords, are not getting through to those that need them.” The Resolution Foundation added: “Both benefit cuts and the end of furlough are pencilled in for the spring, either of which will strain family incomes further. Likewise, unemployment looks set to rise, rather than fall, through 2021, potentially driving up arrears further still.” Trust Deed Scotland said “We speak to hundreds of people every month and most have voiced concerns about their unaffordable debts which typically include the likes of credit cards, catalogues and unsecured loan debt. However, with a number of people having been made redundant in the last year, or who are currently furloughed as part of the Job Retention Scheme – we’ve seen many instances of social and private tenants not being able to afford the repayment of their rent. While there is currently a ban on evictions in Scotland, we’re concerned about the longer-term impact to those individuals’ finances caused by building up rent arrears, as well as other debts, with no clear end in sight. As a result of this, many are falling into a cycle of debt where they are using credit to pay credit and incurring further debt to pay for general living expenses, including priority bills. If you are struggling with unaffordable debt and have dependent children – we also urge you to apply for the School Age Payment award of £250 before the deadline ends on 28th February. The one-off £250 Payment is currently open to families with a child born between 1 March 2015 and 29 February 2016. It can be used for anything from a warm coat to books and toys.”

Support for Scottish tenants with Rent Arrears Debt?

In Scotland, increased support for Scottish tenants in danger of developing rent arrears debt was introduced in December 2020 in the shape of a government-funded Tenant Hardship Loan Fund. The government have set aside £10m for the Tenant Hardship Loan Fund, which is an interest-free loan and is designed to help people who have had their finances or employment impacted by the coronavirus pandemic and do not have other means of housing support. Loans are available for private and social tenants up to a maximum of nine months’ rent costs covering rent arrears and future rent, where those arrears have arisen since 1 January 2020. However, the tenant hardship loan fund will not be available where a tenant had rent arrears before this date. The Tenant Hardship Loan can include up to a maximum of three months of future rent payments as part of the nine-month total. The lending arrangement provides an additional short-term offer that supports tenants to manage rent arrears and helps them to come back into paying their rent. Loan repayments under the tenant hardship loan scheme will be deferred for six months as standard and repaid over a five-year period. The Scottish Government hopes that this helps solve any issues with the continuing uncertainty around the impact of the Coronavirus pandemic. However, as part of the Scottish Government’s commitment to responsible lending, the Tenant Hardship Loan Fund offers will be subject to an affordability assessment. The affordability assessment looks at the applicant’s incomings and outgoings to check whether the applicant has enough surplus income, after other costs, to make the loan payments. Please note: Applications for the Tenant Hardship Loan Fund were discontinued for new applications in December 2021.

Can I include Rent Arrears Debt in a Trust Deed?

The legal position is that all rent arrears should be included in your Trust Deed. However, to avoid any issues with your landlord, especially if you are a private tenant, then you should take advice before considering entering into a Trust Deed whilst you have rent arrears.

Rent Arrears Debt and the Debt Arrangement Scheme

If you have build up rent arrears debt, you may be able to apply for a Debt Payment Programme (DPP) under the Debt Arrangement Scheme (DAS). A DPP, which is a formal debt solution, will give you time to pay off your rent arrears debt at a rate you can afford, and include all other unaffordable, unsecured debts that you are struggling to afford such as credit cards, unsecured loans and council tax arrears. In addition to being able to include your rent arrears debt and credit card debts or other debts that you owe – any interest and charges on those debts are legally frozen, and if you’re receiving distressing telephone calls, text messages and letters threatening you with visits from Sheriff Officers  – you can reduce and eventually stop this type of contact with an approved Debt Payment Programme. The Debt Arrangement Scheme has risks and benefits just like Protected Trust Deeds which have advantages and disadvantages. The Minimal Asset Process route to Sequestration may also be a suitable formal solution for people struggling with unaffordable debt. In order to find out what your options may be suitable for you, Trust Deed Scotland recommends talking to an experienced debt advisor and seeking tailored debt advice, based on your situation.

How to get Scottish Debt Advice today

If you’re worried about your finances and would like to take control of your unaffordable debt, you can contact Trust Deed Scotland on 0141 221 0999, or complete our Trust Deed Wizard tool for more information. As a leading provider of formal Scottish debt solutions including Trust Deeds, and the Debt Arrangement Scheme, our experienced debt advice team are able to work with you and offer tailored debt advice that puts you at the heart of the decision-making process.  

What option for paying off debt is best for me?

The best option for paying off debt that is right for you will invariably always depend on your personal circumstances. We have a free Scottish debt help guide that can be used to work out the differences between each solution and how they may be advantageous for you, plus the disadvantages of each too. It’s always our recommendation to seek advice from an experienced debt adviser, as they will give you the most informed view of which options are best for paying off debt in Scotland. You may recognise any of these 10 traits in yourself when you have unaffordable debts in Scotland, but that alone doesn’t automatically mean you’re in need of a formal solution for your debts.
  1. Paying non-priority bills like credit cards instead of priority bills such as your mortgage or rent.
  2. Borrowing money from family and friends.
  3. Using payday loans to keep yourself rolling over.
  4. Dreading receiving new bills because you know you can’t pay them.
  5. Running out of money within days of being paid.
  6. Your credit and debit card are declined at the shop till.
  7. Using your bank overdraft to get by month to month.
  8. Making minimum payments every month to your credit cards.
  9. Avoiding phone calls and visitors to your doorstep for fear of it being a debt collector.
  10. Pretending everything is ok when it’s not.

Where you can get help today

You can and should seek help from a qualified money advisor as soon as you possibly can. Trust Deed Scotland® can be reached between 9 am and 8.00 pm by calling 0141 221 0999 or you can use an alternative method to contact Trust Deed Scotland. If you owe money to your creditors and you’re starting to receive demands for payment through the post, or by telephone – try and stay calm. The letters are deliberately worded to cause urgency, fear or alarm, so much so that the UK government ordered new debt letter rules to make the letters less intimidating and reduce distress. If you are considering an option for paying off debt that feels rushed, as a result of a creditor pushing you into it – make sure that this isn’t the only motivation for applying for the solution. A good debt advisor will always give you transparent, balanced advice and leave the decision in your hands, at your own pace. If you’re not quite ready to proceed, you can apply for a Statutory Moratorium to give yourself breathing space of up to 6 months from your creditors.

Trust Deeds

An option for paying off debt in Scotland is a Protected Trust Deed. Learn more about what are Trust Deeds and how Trust Deeds work. As a formal, legislated solution, the Trust Deed helps thousands of people make a fresh start every year in Scotland. A Trust Deed typically lasts for 4 years in Scotland and can be used to manage unsecured debts such as credit cards and loans. Once in place, interest and charges are frozen, creditor contact will be reduced from payment demands to mostly administrative notifications such as statements – all of which will be managed by your Trustee. When you evaluate whether or not you feel that a Trust Deed is a good idea or not you for – consider all pros and cons and how they affect you on a personal level. It’s important to seek advice from a qualified money advisor such as Trust Deed Scotland® where you will receive tailored debt advice based on your circumstances.

Debt Arrangement Scheme

Repaying debts under the terms of the Debt Arrangement Scheme is a solution that is growing in popularity. Figures based on official 2018-2019 to 2019-2020 data show an annual increase of 23% for people using DAS to clear their debts and that’s before taking into account figures that are likely to be inflated due to the Coronavirus pandemic and its financial impact on households. When you apply for a Debt Payment Programme in Scotland and it becomes approved, like a Trust Deed any interest and charges will be frozen. Depending on how much debt you have and how much you pay, the length of time to repay may be quicker, or longer than that of the Protected Trust Deed. Regardlessly, you will have a fixed end date in mind, which may then be shortened depending on your affordability and whether your personal circumstances were to change in a positive way. Learn more about what is a DAS and the advantages and disadvantages of the Debt Arrangement Scheme as a potential option for paying off debt for you.

Minimal Asset Process vs Full Administration Bankruptcy

The Sequestration (Scottish bankruptcy) method is another option for paying off debt in Scotland. It’s possible that a creditor can petition for your bankruptcy and remove the decision from your hands, if this is a concern for you – give us a call on 0141 221 0999. Sequestration or Bankruptcy in Scotland arguably carries the greatest stigma, yet while it may be considered as a last resort for many, the reality is that it can be the most effective way of clearing your unaffordable debts and moving forward in life. The sequestration process is effectively divided into two categories – Minimal Asset Process and Full Administration Bankruptcy. There are setup fees usually for these two products, however, recent legislation changes to MAP Sequestration mean it is now free to apply for. With Full Administration Sequestration, those fees have reduced these fees to a lesser amount of £150, depending on the individual’s income. If you are in receipt of certain benefits, the Sequestration too may be processed for free.

An alternative option for paying off debt in Scotland?

There are other alternatives that can be viable options for paying off debt in Scotland including an informal Debt Management Plan, or a Debt Consolidation Loan. You can find out more about the differences between a Debt Management Plan vs. Debt Arrangement Scheme but essentially the main difference between one and the other, is that the DMP is informal and the DAS is formal. Debt consolidation is perhaps the most commonly known overarching term for all debt solutions available in Scotland. This can help create a view that the only way to manage debt is to borrow more money in the shape of a larger amount of money and then consolidate those debts down to one, either by using a credit card or a loan. However, while there are benefits to doing so, the reality is that finding funds at a favourable rate is less likely. More often than not, with a poor credit rating and a history of defaults – the only loans that may be made available to you are a secured loan against your property or a guarantor loan using someone else to repay the debt on your behalf. We tend to advise against both of these solutions, but given the right circumstances, you may feel different, or they may work for you. Call us on 0141 221 0999 to find out more about how we can help you consolidate your debts. Find out more about the differences between an unsecured loan and a secured loan.

Will Trust Deed Scotland® be able to help me?

When you seek help with your debts it can be a worrying time. It is a big step, one which Trust Deed Scotland® fully understands and undoubtedly, people may be worried about doing so. You may worry about the reaction you will get from a stranger, and you may fear that the people you are speaking to will be shocked, will disapprove or judge you. On top of that, there is a stigma surrounding the debt advice process itself. What does it involve and what do all these abbreviations all mean? Debt advisors should never be judgemental and should always advise you on what’s in your best interests, not their own. If you feel they are pushing you into a solution without properly explaining it, seek qualified debt advice elsewhere. You should NEVER pay to receive debt advice, and no solution should have upfront setup fees; other than those required directly for Sequestration, should you not be exempt from paying the £150 application fee for this. Trust Deed Scotland® feels proud of our debt advice reviews as they indicate how our customer feel about our service in their own words. With over [reviews] reviews on Trustpilot, we’re rated excellent in their Debt Relief category, and with more five-star reviews than anyone else – we’re the No.1 rated in the category as well. Call us on 0141 221 0999, or try our Trust Deed Wizard® tool to get started.

What is Zombie Debt?

Halloween 2020 is set to look different than any other in Scotland with the Scottish Government asking us to avoid guising and thus help prevent spreading Coronavirus. Residents of Scotland with old debts beware: a forgetful moment from your past could results in old debts rising from the dead and coming back to haunt you. Zombie debt. So, as we’re at home this Halloween, we’ve put together a guide to help you understand more about what you’re options are. Helping you to avoid having a night of the living debt.

What are Zombie Debts?

Zombie debts are old accounts that may have been forgotten about and then either written off as ‘uncollectable’ and which have passed the time in which they can legally be collected. These can be anything from an old payday loan to a credit card debt. Even an old library fine. Depending on the type of debt and how old the debt may be, you may be in for a nasty surprise, or it may become unenforceable due to becoming a Prescribed Debt, known more commonly across the UK as Statute Barred.

Are my statute barred debts written off?

A regulatory body say that it’s not fair for a creditor to keep asking you to pay a statute-barred or prescribed debt if you’ve told them you don’t intend to pay it. In Scotland, If the creditor waits too long, the debt will become prescribed. Once a debt is prescribed, the law says it no longer exists so there’s nothing more the creditor can do collect it. This is outlined as part of the Prescriptions and Limitation (Scotland) Act 1973. Statute barred debt in England refers to a debt that’s not enforceable because the time a creditor has to chase payment has passed. This is outlined under the Limitation Act 1980. In England, Wales and Northern Ireland where under the Limitation Act 1980, a creditor has six years to chase most unsecured unpaid debts or twelve years for some mortgage shortfalls. This ‘limitation period’ starts from the time of your last payment or acknowledgement of the debt, not the total length of time you’ve been making payments. The Limitation Act 1980 act states that when all of the following conditions are met a debt cannot be enforced:
  • The creditor has not registered a CCJ against you (Known as a Decree in Scotland)
  • You have not made a payment in the last six years (or with joint debts, the other person)
  • You have not admitted the debt in writing in the last six years
  • Where it’s a mortgage shortfall, the latter two restrictions are doubled to 12 years.
For most types of debt in Scotland, the prescription period is 5 years. Mortgage capital shortfalls have a longer prescription period of 20 years for the money that you borrowed while the interest charged on this has a prescription period of 5 years. Council tax and overpayment of social security benefits are also subject to a prescription period of 20 years. If your creditor has already started action to obtain a Decree before the prescription period passed, the debt can’t become prescribed.

How did I get a Zombie Debt?

Zombie Debt comes in many forms, including legitimate debts that have been forgotten or ignored, Identity theft cases and I.T. errors. The most common way of this happening is a combination of change of address, change of telephone and changed bank details. With no little way of knowing, we assume the debt has been paid and eventually may believe that we paid it off. If you have built up a zombie debt and forgotten about it, don’t feel bad about it – it’s an easy oversight to make. But, if you have forgotten about a debt you are protected from harassment or any other contact from the creditor. You cannot be pursued through the courts, as the debt is deemed to have either been abandoned or repaid. It involves unsecured credit from credit cards, store cards and the likes of council tax arrears. It does not apply to secured debt such as mortgages and money owed to the government for income tax, property tax, fines and student loans.

Help with unexpected debt?

If you have unaffordable debt, whether it’s from an old Zombie Debt, or more recent – You should always look for expert debt help in Scotland. You can find out more about Trust Deed Scotland and find out why we’ve become the No.1 rated company in Trustpilot‘s debt relief services category. If you are struggling with debts, we’re here for you. You’re not alone. Find out more about what is a Trust Deed in Scotland or about what trust deeds do, call us today on 01412210999 for friendly, non-judgemental advice.  

Are Credit Cards included in Scottish Trust Deeds?

All types of unsecured debts are required to be included within a Scottish Trust Deed and credit cards are the most common type of debt that is included in Trust Deeds and alternatives such as the Debt Arrangement Scheme.

What are Credit Cards?

Credit cards and store cards are both used to purchase goods and services on credit in the same way that a catalogue accrues a debt, or a personal loan, bank overdraft and so on. A debit card is different to a credit card as it relies on finds being active in an account. Credit cards may be issued by your bank or building society, or other financial services provider. A credit facility may be provided by a high street store for example, more commonly referred to a store card.

Are Credit Cards a problem?

We’re a nation of credit card enthusiasts. The Money Charity reported in July 2020 that the average credit card debt per UK household was £2,238 in January 2020. Credit cards are convenient and handy. They’re useful for travelling and in some cases, they do offer greater protection for purchases and reclaiming where a transaction has resulted in a poor buying experience. Chargebacks themselves are really useful. A chargeback is a refund prompted by your card issuer. If you paid for a product or service with a credit card, you can dispute it through the card issuer and let them take the dispute to the merchant. If the issuer succeeds where you failed, the purchase price is refunded to the credit card you charged it on. However, as credit cards become more readily available, and the numbers of people relying on them continue to grow, defaults are becoming more common. Store cards carry with them a different level of threat. The store card may seem like its a loyalty card, being used to open with an immediate discount. However, with little room for competitive rates, the interest rates are often unfavourable, to begin with, and comes with the added temptation in the form of buying there and then, in the store.

How to manage Credit Card debt?

If you have a temporary payment problem, contact the card issuer to discuss this. They may offer some short-term flexibility and with payment breaks being replaced with ‘tailored’ solutions as a result of Coronavirus recommendations made by UK regulators. If you haven’t defaulted on your credit cards and have a great credit rating, you can shop around for other credit cards which allow interest-free balance transfers. Caution should be used when examining the small print. Credit card lending is done based on risk. The more of a risk you are, the worse the interest rate you are likely to achieve as a result. Will you be able to afford new lending terms over the longer term. However, if like many thousands of other households in Scotland, your money issues are more serious, it’s best to get expert debt advice. A qualified money adviser can take a look at your situation, advise you of the options and allow you to make a balanced decision. Solutions for credit card debts in Scotland may include the Scottish Trust Deed, Debt Arrangement Scheme or Sequestration.

What is a Scottish Trust Deed?

The Scottish Trust Deed is more formerly known as a Protected Trust Deed and is used to consolidate debts over a typical period of 48 months. It’s a government legislated debt solution that allows an individual to freeze interest and charges, pay back a more reasonable amount to their debts and protect assets such as a home or car. There are disadvantages too such as an impact on your credit rating. When you have unaffordable debts such as credit card debts, the Scottish Trust Deed solution may work for you.

Alternatives to a Scottish Trust Deed?

The Debt Arrangement Scheme is a solution that also allows you to legally freeze interest and charges, stop creditor harassment over non-payment and gives you a fixed time frame for when you will be able to repay the debt. When evaluating your options – we recommend speaking to a qualified money advisor and that will allow you to receive tailored advice depending on your circumstances. In addition to the Scottish Trust Deed or DAS, you may consider Bankruptcy as a way of managing your debts. Sequestration and Minimal Asset Process are the two forms of bankruptcy that are used in Scotland, and while they may carry the severest of impacts to a credit rating and come with a natural stigma attached to them – They are an effective way of clearing debt.

Help with Credit Card debts in Scotland

We’ve helped over [volume] people in Scotland, became the No.1 rated with more Trustpilot debt advice reviews than anyone else in Scotland. Every week, our experienced debt team give hundreds of people non-judgemental and confidential advice. Call us on 0141 221 0999 or learn more about Trust Deed Scotland today.