Google crackdown on misleading debt service ads

Google has restricted its advertising product availability for bogus debt companies in a move welcomed by Trust Deed Scotland®.

You can read our article on the Daily Record here

Any debt advice firm wishing to advertise on Google will be forced to provide official accreditation of a UK regulatory body before being allowed to advertise on Google.

Amanda Hendry of Trust Deed Scotland® advised “We’ve been aware of a number of firms operating, passing themselves off as the official Trust Deed Scotland® for a number of years now. Remarkably, these ‘lead generation companies’ can come as far away as India, the Philippines and more commonly from call-centres based in England.

Not only does this cause uncertainty in the market but it also opens up consumers to receiving advice below a standard that we here at the official Trust Deed Scotland® pride ourselves upon.

We have heavily invested in our own compliance and call recording technology and regularly commit our advisors to regular training sessions.”

Trust Deed Scotland® have been helped over [volume] people in Scotland by providing Debt Help in Scotland.

A growing concern

There have been over 83 instances of fraudulent impersonator websites reported for advertising on the platform in 2019 as a debt charity, an increase from 46 the previous year. A staggering 80% increase.

Trust Deed Scotland® added “People who need financial advice are often vulnerable and susceptible to calls and online offers from individuals offering ‘government approved solutions.’

This, in fact, can result in a worsening of their finances as those companies then aim to sell their details onto effectively the highest bidder.”

Matthew Lavine, of Google who is employed as a product policy specialist, said of the issue: “This is the culmination of extensive work by our policy teams globally and we have listened to and consulted with debt advice charities and other organisations whose users will benefit from this policy.”

Spoofing

Likewise, there has been an increased number of ‘spoofed’ numbers in the industry. This is the practice of rogue companies changing caller ID screens using VoIP technology from abroad to mimic the telephone numbers of known debt companies such as Trust Deed Scotland® an issue that Ofcom are working with international regulators to find solutions for alongside

The Internet Engineering Task Force (IETF), which helps to develop standards on the internet. Together they have created a group designated to solving this problem.

If you ever receive a call from a company pertaining to be from Trust Deed Scotland®, remember that the official Trust Deed Scotland® will never buy your data from a third party, nor pass your data onto any other 3rd party.

You will never receive a cold call from Trust Deed Scotland®. If in doubt, hang-up and contact the official Trust Deed Scotland® on 0141 221 0999.


What is the difference between a Trust Deed and a Deed of Trust?

The two are completely different, but we still see that it confuses people what the difference is when they’re searching on Google! As a result, below you will find the difference between a Trust Deed and a deed of trust to help you on your way to finding more about what you need.

What is a Trust Deed?

If you’re struggling financially and require debt advice in Scotland or support on how to move ahead, an advisor may make you aware of the opportunity of entering into a Trust Deed. Before you do so, you should ensure that you understand what a trust deed is, how it works and be aware of other debt arrangement schemes available. A Trust Deed is a voluntary agreement between you and your creditors (who you owe money to) to repay what you owe. It’s a formal debt solution that’s only available to Scottish residents who have a personal debt of £5,000 or more. A Trust Deed can be particularly helpful if you’re struggling to pay your debts within a reasonable timeframe – five years, for example. It’s generally a more straightforward and less restrictive alternative to declaring bankruptcy and can be used to pay off part of any “unsecured debt”, such as money borrowed using credit cards and loans. It’s important to note that social security benefits and things like Universal Credit can be taken into account to assess your situation when you apply for a Trust Deed, but the contribution you pay back will not be taken from these funds. Generally, only disposable income is used to pay creditors, but other assets such as furniture could also be liquidated to help make contributions, but this will have been agreed with your advisor before entering a trust deed. The financial advice on offer meanwhile when you enter into a Trust Deed can include remortgaging, but this is not mandatory and typically not advised unless a final option. There are two types of trust deed – protected and unprotected. An unprotected trust deed is not binding for a creditor (company or other) who doesn’t agree to the terms. A Protected Trust Deed meanwhile is binding for the creditor, although they have a 5 week period in which to appeal. It’s in the interest of the trustee to have the trust deed protected, but it’s not essential. It is also worth noting that a trust deed debt must be a minimum of £5,000 to become protected. You should be aware that all protected trust deeds that fall under the court of session and within the territorial jurisdiction of Scotland are advertised as a public record in the AIB register. It is also likely that setting up a trust deed will affect your credit record. Trust deeds can only be administered by a licensed insolvency practitioner.

 What is a Deed of Trust?

what is a deed of trust

Although similar in name, a deed of trust is something entirely different from a Trust Deed. A deed of trust is an important document (governed by The Trustee Act 2000) in which trustees are appointed to hold the property for beneficiaries. A Deed of Trust can be used to state how a property is owned. For example, the property may be owned by several parties, each with a different contribution towards the ownership, and this proportion of ownership may not be listed in the land registry. A deed of trust enables someone to be a protected owner of the property, even if they are not a registered owner with the land registry. A Deed of Trust can be necessary for various circumstances. For example, say that someone wishes to contribute towards buying a new house with their partner. However, they are already the owner of a property with a mortgage, so they cannot be part of the mortgage on the new house. A deed of trust can be used to register their contribution towards, and ownership of, the new property, while their partner is listed with the land registry as being the sole owner.

What is a trustee in a Deed of Trust?

A trustee is somebody who manages the property that is held in a deed of trust. Trustees are entrusted to act in an appropriate manner, and always in the interests of the beneficiaries.

What is the difference between a Trust Deed and a Deed of Trust?

So how does a Trust Deed in Scotland differ from a Deed of Trust? A Trust Deed is an alternative to bankruptcy in Scotland and involves a professional overseeing your repayment of debt over a certain amount of time to your creditors. A Deed of Trust meanwhile is a legal document most commonly related to the ownership of property and involves a trustee managing how it is really owned, enabling your percentage of ownership to be protected, even when you are not listed in the land registry as the owner. To find out more about Trust Deed Scotland and if you qualify for a Trust Deed, try our Trust Deed Debt Calculator. Debt Help Scotland  ✓ 30,000 people helped ✓ No.1 Rated ✓ Tailored Advice ✓ No Setup Fees.

5 Trust Deeds Questions

When it comes to trust deeds, there are certain questions people commonly have. Here at Trust Deed Scotland, we’ve compiled 5 Trust Deeds Questions, as well as the answers to each of them, to help you stay in the know.  

What is the difference between a trust deed and sequestration?

Trust Deeds differ from sequestration, or bankruptcy, in a number of ways:
  • A trust deed is less formal than sequestration and doesn’t involve the court – it’s a private contract between you, your trustees and your creditors
  • If you’re a homeowner, you can still keep your home if you enter a Trust Deed
  • Unlike sequestration, you can borrow money without disclosing your status, be a company director, and qualify for elected public office
Where they’re similar, though, is the minimum period for contributing to an insolvency estate. Recent legislation changes have increased this time for sequestrations from three years to four, on par with trusts deeds. This is thought to be the main reason why trust deeds today exceed sequestrations, according to government statistics – with no difference in the period of contribution, more and more people are shunning bankruptcy and going for the more ‘positive’ trust deed option.  Yes, a trust deed does affect your credit rating. This is because entering one means you’re breaching the original terms of your credit agreement. However, remember that if you’ve already missed credit payments or are paying your creditors decreased amounts, your credit rating may have been negatively affected, to begin with. After you’ve completed a Trust Deed, it will show on credit reference agency files for another two years. Your credit rating will stop mentioning it when six years have passed since you first entered a trust deed.

When does a Trust Deed become protected?

A trust deed becomes protected once the majority of your creditors (two-thirds by debt value, or more than half by number) agree to the proposal. They can then no longer contact you for any reason or start any legal proceedings against you to recover debt. However, you should know that even after your trust deed becomes protected, your trustees or creditors can still seek for your sequestration if they’re able to prove that it will give more back to your creditors than what a trust deed would. For more information on the Debt Arrangemennt Scheme, see our related article What is a DAS?

What is the minimum debt level required to take out a trust deed?

The minimum debt level needed to enter a trust deed with Trust Deed Scotland is £5,000 (as compared to £3,000 for sequestration). Keep in mind that there are some trust deed providers that may require higher levels of debt for them to take on your case. And of course, you also need to have been a resident in Scotland for a minimum of six months and have an income, or someone willing to act as a third party, for you to qualify for a trust deed.  

Trust Deeds Questions – Additional Queries Not Answered Here?

Setting up a trust deed with Trust Deed Scotland is easy. Enter your details on our website or call our office to arrange a free meeting with one of our debt advisors, who’ll then let you know all your options and help you find the best debt solution for you. Once we have all the information we need from you, we’ll start drafting your case. At this point, we’ll also help you set up your first trust deed payment, which means you can immediately stop any current payments to your creditors. Before you start setting up a trust deed, though, try our Trust Deed Wizard to see exactly how one could help you become free of debt. There are many more than just 5 Trust Deeds Questions. There are other alternatives in Scotland too. Get answers to more of your questions about financial options on our debt solutions.

Scottish Trust Deeds On The Rise

Article written in 2016. Some terminology may have changed since then. If in doubt, contact us for clarity and the most recent interpretation of the information provided. The latest government Protected Trust Deed data indicates that Scottish Trust Deeds are on the rise in Scotland. But what does that mean for Scottish people? Let’s look at the insolvency statistics for Scotland this year, and find out.

How Do the Insolvency Statistics Differ from Those in Previous Years?

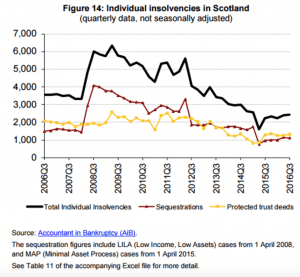
The government’s insolvency statistics for Scotland in the third quarter (July to September) of 2016 show that: ⚫ The number of individual insolvencies increased by 8.5% compared to the third quarter of 2015, with 2,424 recorded. ⚫ The number of individual sequestrations (bankruptcy) increased by 15.3% compared to the third quarter of 2015. Of the 1,113 in Q3 this year, 471 people went into sequestration through the Minimal Asset Process route. This replaced the LILA route (Low Income, Low Assets) in April 2015, which has led to a general decrease in sequestration filings. ⚫ The number of individuals applying for a trust deed increased by 3.3% compared to Q3 2015, with 1,311 filings. ⚫ The figures for all three quarters also display that for the first time in a long time, significantly more people have been filing for trust deeds than sequestrations. Looking at the figures for Q2 2016, the 1,261 trust deed filings saw a 48.5% rise compared to Q2 2015, while Q1 2016’s 1,235 was an increase of 48.1%. The rise in 2016, and how it compares to previous years, can be seen with ease on this graph of the Q3 data for individual insolvencies. While the numbers of individual trust deeds have occasionally matched or very minutely exceeded the number of sequestrations, the last time we saw this kind of change was back in 2007.

Why Have Scottish Trust Deeds Exceeded Sequestrations?

Insolvency legislation has recently changed with regard to the minimum period for contributing to your insolvency estate. While Sequestration‘s used to require a minimum period of three years, now both Sequestrations and Trust Deeds demand a minimum of four. This is most likely the reason for the rise in trust deeds – with no difference in the period of contribution, people are choosing the more positive option of a Trust Deed, than straightforward bankruptcy.

How Many People Have Applied For Trust Deeds?

Looking at the data from Q1, Q2 and Q3 together, you’ll see that 7,061 Scottish people have filed for bankruptcy so far this year, yet only about 4,000 have applied for a Trust Deed. This shows that we need to be reaching those other 3,061 people to try and show that Trust Deed Scotland is a strong alternative (as long as the debt is more than £5,000).  

What Is A Scottish Trust Deed?

If you’re asking the question of what is a Scottish Trust Deed at this stage, then the simplest explanation is that a trust deed is a voluntary arrangement whereby you effectively cover your debts through your own assets, rather than going into sequestration. Your contribution to your trust deed is based on how much disposable income you have once your living costs have been deducted from your income. To be eligible for a trust deed you have to be a Scottish resident with £5,000 or more unsecured debt.

Can You Get A Scottish Trust Deed Twice?

Yes. You can apply for a Scottish Trust Deed twice, and it is not uncommon for people to fall into financial difficulties again after originally clearing debts using this tool. Statistically, it is rare for individuals to need a second Trust Deed but such is life, some people may find themself in a similar position. You can have 2 Scottish Trust Deeds, but you must also be discharged from the first Trust Deed which means that the first Trust Deed has ended, either because it failed or you had complete the term. If you have failed a Scottish Trust Deed and you’re looking at being discharged – it’s important that all factors are considered and alternative solutions discussed. Trust Deed Scotland offer non-judgemental confidential advice and advise you to give us a call on 0141 221 0999.

What Does This Mean For Scottish People?

As we discussed earlier, the change in legislation for declaring yourself bankrupt has seen a rise in people filing for a trust deed. Many people who are in debt are happier once they have a trust deed, as it means that you are only making one payment a month to one body, rather than several to different creditors. Those who set up a Scottish Trust Deed with Trust Deed Scotland should also be confident that they are receiving support which puts them first – as evidenced by our no.1 rated status. With a less negative connotation than Sequestration, and support which puts people, not money, first, this rise in Scottish Trust Deeds should help to remove the stigma of being in debt, and show that bankruptcy is not the only option. For free, impartial Debt Advice In Scotland – call 0141 221 0999

Aberdeenshire Property Affordability

Worried about Aberdeenshire Property Affordability?   After a brief hiccup in house prices after Brexit, confidence has returned to the housing market in Scotland, and with a shortage of properties on the market, demand for high-value houses remains high from overseas buyers. But how affordable is owning a dream property for Scottish homeowners? According to a recent report from MORE TH>N, almost half the average UK homeowner’s monthly income now goes towards essential home costs, such as utility bills, insurance and maintenance. Aberdeen comes out as the second most expensive area in Scotland to run a home, with an average home maintenance bill of £1,682 per month. So how much might it cost you to run your ideal country pile? We take a look at five of the most expensive (and gorgeous) properties recently for sale, and see how much we’d get stung. 1. Invery House, Banchory, Kincardineshire, AB31 Yours for: £2,500,000 What you get: – 10 en-suite bedrooms – Billiard room, gymnasium and wine cellar – Kitchen with triple Aga and larder room – A “staff wing” with 2 en-suite bedrooms – Coach house and stables – 30 acres of land EPC rating*: F

Likely cost to run: c. £121,000 (£10,000 a month)

The cost of maintaining this sprawling Georgian pile – and its outbuildings and grounds – could be crippling.  In 2014, Country Life estimated the cost of running a large country house at £115,950 a year or £9,662 a month, including staff costs, council tax and repairs. However, the oil-fired Aga stove could add an extra £5,000 a year onto the bill alone.  

2. 5 bedroom detached house for sale, Milltimber, Aberdeenshire, AB13

Yours for: £1,775,000 What you get: – New-build luxury detached house – 5 large bedrooms, 5 reception rooms – Triple integral garage with electric doors – 0.5 acres of garden EPC rating*: B

Likely cost to run: c. £31,000 a year (£2,583 a month)

Being a new-build, there are no crumbling, listed features here to be maintained, and it’s pretty energy-efficient. However, you’re still looking at a hefty price tag for the buildings insurance alone – perhaps £1,000 a year – plus security costs of around £500 a year. And a gardener adds another £15,000 or so on top.  

3. Balbithan House, Kintore, Inverurie, AB51

Yours for: over £950,000 What you get: – Category A-listed baronial house – 9 bedrooms, 4 reception rooms, library – Garage, workshop, greenhouses, potting shed – 9.75 acres of gardens and woodland – Turrets and a spiral staircase EPC rating*: F

Likely cost to run: At least £46,000 a year (£3,830 a month), depending on repairs required.

This impressive house dating back to the 16th century has oodles of original features. That, plus the Category A listing, makes it a very expensive property to take on. Utility bills are likely to hit at least £4,500 and you’d need to budget around £500 a year to maintain the chimneys. And if something goes wrong with that roof, the sky’s the limit on repair costs.  

4. Fae-Me-Well House, Cothal, Aberdeen, Aberdeenshire.

Yours for: over £760,000 What you get: – Period home with self-contained annex – 7 bedrooms, 3 reception rooms – 3 garages – 3 acres of landscaped gardens EPC rating*: unknown

Likely cost to run: Around £29,700 a year (£2,475 a month)

This 19th-century converted farmhouse has great rental potential. But with seven bedrooms, plus one in the annex, utility bills could top £3,300 a year. Rental income on the annex would offset some costs, but you’ll have to pay separate council tax and water rates for it.  

5. Countesswells House (South Wing), Bieldside, Aberdeenshire

Yours for: over £915,000 What you get: – B-listed country house – 5-6 bedrooms – Greenhouse, sheds, summer house – 4 acres of landscaped grounds EPC rating*: unknown

Likely cost to run: Around £26,700 a year, or £2,225 a month.

  This 18th-century-period house has been converted into two residences, and the roof has recently been renovated, so maintenance costs should be relatively low.   Still want that dream house in the country? We’ve seen that a rural idyll could put the richest homeowners under pressure. But with rising inflation, all homeowners and renters in Scotland are now feeling the pinch as energy bills soar. With winter 2016/17 looking like a cold one, now’s the time to take stock of how much your home will cost to run over the next six months – and whether you’ve got enough savings to deal with something unexpected should the worst happen. Are you feeling the pinch, and worried about getting more into debt? Use our Trust Deed Scotland® debt calculator. *An EPC rating (Energy Performance Certificate) indicates how energy efficient a property is, ranging from A (most efficient) to G (least efficient).

4 Things Brexit Could Mean For Scotland

what the Brexit means to Scotland Most people in Scotland didn’t want it, but it’s happening: the UK has voted to leave the European Union. Take a look at 4 things this truly seismic result could mean for Scotland.

1. Another independence referendum

First minister Nicola Sturgeon has, in the past, come close to suggesting a second independence referendum should Britain vote for Brexit. This week, Sturgeon will meet European Commission president Jean-Claude Juncker in Brussels to discuss the outcome of the referendum. It’s thought Sturgeon will stress to Juncker that Scotland wants to remain inside the EU, potentially as an independent country. It’s been reported that Sturgeon is gearing up for a second vote, should Westminster approve it.

2. A complete block on leaving

It’s also been suggested that the Scottish parliament could completely block the legislation necessary for the UK to part from the EU. Sturgeon has said: “If the Scottish parliament is judging this on the basis of what’s right for Scotland, then the option of saying we’re not going to vote for something that’s against Scotland’s interests, that’s got to be on the table. You’re not going to vote for something that is not in Scotland’s interests.” With 62% of people in Scotland backing Remain and only 38% backing Leave, Sturgeon could argue that she has the will of the people on her side. However, it’s unclear whether the Scottish parliament really does have the necessary authority to veto Brexit.

3. Dual citizenship?

Some people are thinking of taking dual citizenship with Ireland, which has been an EU member since the 1970s. Theoretically, if there is a second independence referendum, dual citizenship could be an option in Scotland too. The Scottish government has said that:
  • British citizens born in Scotland would be automatic citizens of Scotland.
  • British citizens “habitually resident” in Scotland at the time of independence will also be automatically considered.

4. More support for business

Scotland is well-known for its emerging industries – gaming, new energy and life sciences, to name just a few. In the wake of Brexit, the government has moved to reassure businesses they have a bright future. Cabinet secretary Keith Brown has said: “I have been engaging extensively with the business community in Scotland over recent days to emphasise that, as of now we are still firmly in the EU. Trade and business should continue as normal and we are determined that Scotland will continue now and in the future to be an attractive and a stable place to do business.” What are your thoughts on the implications of Brexit for Scotland? Let us know. Thinking of taking out a Scottish Protected Trust Deed? Read our Scottish debt solutions FAQ guide and get top tips and financial insight on our info hub.

The Devastating Impact of the Scottish Energy Industry Slump

British manufacturers are set to cut tens of thousands of job next year as the Scottish energy industry continues to struggle. The decline of the oil industry and the collapse of the steel trade has created a range of problems that have spanned the lengths and breadth of the country. Aberdeen has been particularly affected by the downturn with many job losses affecting not only those in the oil and energy sector but in the hotel sector and other industries. It also affected homeowners planning to sell their properties as they are no longer as desirable as a result of the job losses and lack of employment. In 2006, the average house in Aberdeen cost £312 000 with some houses selling for upwards of £3 million. This is in stark contrast to the figures at the end of 2015 which show the average price has dropped by 28% to £225 000.

Help is available for Scottish residents in debt

If you need help with your finances, Trust Deed Scotland may be able to help you get back on track. Try the Wizard tool to find out how a Trust Deed could help write off a percentage of your debt and solve your money worries. Aberdeen airport’s minimum ATM withdrawal is £200, a reflection of the affluence of the clientele who pass through its doors daily including oil workers, executives and engineers. People from this industry who are being laid off are experiencing difficulties adapting to lower paid work as they may already expensive financial commitments to maintain which they took on with the expectancy of earning a high salary. A spokesperson at Trust Deed Scotland observed: “The number of people from Aberdeen enquiring about Trust Deeds has been rising for the past few months and that is most likely due to the lack of employment in the oil and gas business. People are having to change careers and take a very large drop in wages. Last week we spoke to a person who had become an HGV driver after redundancy from the oil sector and is now struggling to get by from month to month. People who were used to a certain standard of living are having to be very stringent.” Manufacturers’ organisation EEF said the factory sector may grow by a small amount in 2016 but a downturn in China is poised to trigger a global slump. The cheap prices of Chinese steel were blamed for the closures of Scottish steelworks which forced thousands into unemployment. Thousands of further jobs are at risk after British OGN failed to make the shortlist for a major North Sea contract on offer from US group Chevron. They appear poised to offer the contract to companies out with the UK, despite the fact OGN have a track record of success. Mary Glindon, MP for North Tyneside where OGN are based commented, ‘If we lose this contract I am petrified that it could lead to closure and that is the end. Once a business closes then it is rare for it to reopen.’ Chairman of OGN, Dennis Clark confirmed as many as 3000 jobs at the Wallsend yard and in other areas of the company are at risk because there is no major work confirmed for the company within the next three years.

Scottish Energy Sector Employees – Debt Help

If you are currently, or were formerly working in the Scottish Energy sector in a self-employed capacity, explore our Small Business debt help page for more info. For information about help with your personal finances, see our FAQs or Contact Trust Deed Scotland.

Trust Deed Scotland Client Survey

TDS Oct 2015 Survey   The Trust Deed Scotland October 2015 Survey results showed the top reasons people in October 2015 entered a Trust Deed and helped shed some light on the experiences people have when learning about Trust Deeds. 73% of participants said they were prompted to enter a Trust Deed. 9% entered one as they were threatened with sequestration due to council tax arrears and a further 9% said they chose a Trust Deed as they wanted to improve their credit quickly.

Survey highlights interesting Trust Deed Scotland statistics

Trust Deed Scotland do not cold call customers and were amazed to find out 100% of people surveyed have been cold called by companies offering Trust Deeds. The survey also revealed that although 73% of clients surveyed has spoken to other companies, whether of their own volition or due to cold calls, they decided to approach Trust Deed Scotland to provide their debt solution. The main reasons for this were word of mouth and the Trust Deed reviews written by our happy clients. It was reported in September 2015 that Trust Deed Scotland clones impersonated our identity in order to gain business. The survey results have supported these findings, with over a quarter of participants reporting they were contacted by copycat companies stating they were Trust Deed Scotland and trying to set up appointments. The survey revealed 100% of people rated the information available on the Trust Deed Scotland website as 5/5. 100% also reported Trust Deed Scotland effectively answered any queries they had before they made the decision to proceed with their Trust Deeds. Finally, the service provided by Trust Deed Scotland was rated as 5/5 by 100% of people surveyed. If you have been experiencing financial difficulty, a Trust Deed could be the right solution for you. It allows you to make one affordable monthly payment and leave you enough income to cover your other monthly necessities. You will also be granted debt forgiveness, which means if your agreed Trust Deed terms are met, you will not have to pay back your debt in full and can begin to rebuild your credit score. For Scottish Debt Advice call us on 0141 221 0999 to see how a Protected Trust Deed or alternative could help you.   For more information about Trust Deeds, Contact Trust Deed Scotland.

10 Common Trust Deeds Questions

We often receive calls at Trust Deed Scotland from people asking questions about Trust Deeds. We’ve compiled a list of some of the most commonly asked questions so that you can learn more about the process.

1. How do I set up a Trust Deed?

First common trust deeds questions answered – Enter your details onto the website to arrange a call back, or call the office to arrange an appointment with an experienced debt adviser. The advisor will explain all the options available to you and you can then make an informed decision on whether to proceed with a Trust Deed or another solution. If you decide you would like to proceed with a Trust Deed, we will draft your case as soon as we have received the necessary documentation. Your advisor will give you a checklist of the necessary information. Once your case is drafted, you will receive a call from the insolvency practitioner to confirm the details in your paperwork are correct. After this, your advisor will arrange a final meeting with you to finalise the paperwork and answer any questions you may have. Finally, they will help you set up your first contribution payment and once this is done you can stop paying your creditors directly. Always check with your insolvency practitioner to make sure everything is finalised and you are at the stage where you can cancel payments to your creditors.

2. What if I own my own home?

Second common trust deeds questions answered – You can enter a Trust Deed if you own your own home or if you are a tenant, or living with parents or family. At the beginning of the process, you will be given the opportunity to complete a 1b form which ensures your property is protected, provided you meet the terms of your Trust Deed.

3. Will it cover all my debts?

Third common trust deeds questions answered – It would cover all unsecured finances, excluding student loans or any charges incurred due to fraudulent benefit claims or court fines accrued relating to this. There may be some typical exclusions or grey areas such as a guarantor loan. However, these would be investigated and our debt experts would ensure that any doubt would be immediately resolved, or explained. Remember too that other solutions exist such as Debt Arrangement Scheme.

4. Will I need to have a credit check done?

Fourth common trust deeds questions answered – No, you will not need to have a credit check carried out but a credit check could help verify you creditors and the amounts you owe. This is a good idea if you have additional debts you may have forgotten about or are unsure about who you owe money to.

5. Is a Trust Deed the same as bankruptcy?

Fifth common trust deeds questions answered – No, Trust Deeds and bankruptcy, (called sequestration in Scotland), are not the same. One of the major differences between the two is, if you are a homeowner, you can keep your own home in a Trust Deed but this isn’t always possible with bankruptcy. Click on the following links to find out more about Sequestration and Minimal Asset Process, (MAP). Try the Trust Deed Wizard to see how a Trust Deed could help you. Or, find out how it works.

6. Do I have to tell my family or friends?

Sixth common trust deeds questions answered – As long as you have individual debts, (they aren’t joint with anyone), you do not need to tell anyone at all if you don’t want to. We will never disclose your status to anyone and all correspondence will be discrete.  

7. What if I am self-employed?

Seventh common trust deeds questions answered –  You can apply for a Trust Deed if you are self-employed as long as you can provide evidence of income, accounts and invoices.  

8. What if I stop paying my agreed monthly contribution?

Eighth common trust deeds questions answered – If there is a valid reason you cannot pay your Trust Deed contribution, contact your insolvency practitioner immediately. It is possible to arrange a payment holiday for extenuating circumstances. If you stop paying your agreed contribution without good reason or without contacting your insolvency practitioner, they may discharge themselves from your Trust Deed, meaning your creditors will resume chasing you for the full outstanding balances, they may request a wage arrestment against you or you could be made bankrupt.  

9. Will my credit rating be affected?

Ninth common trust deeds questions answered – Yes, your credit will be affected but if a Trust Deed is the best option for you, it is best to take charge of your finances as soon as you can. If you have not defaulted on any payments but have a high level of unsecured debt, you will find yourself in the position where lenders will not consider giving you any more credit, even if you have a high credit score. This is because the acceptance process is means-tested and even if you have never missed a payment, there will come a time when what you owe exceeds the realistic probability that you can pay it back based on your income and expenditure.  If you have already defaulted on payments to your creditors, your credit will already be negatively affected and each default will show on your credit file for 6 years. Once you have been discharged from your Trust Deed, you can rebuild your credit.  

10. What would a Trust Deed mean for my future?

Tenth common trust deeds questions answered – all debts included in your plan will be written off and you are now able to rebuild your credit score. This would allow you to apply for mortgages, higher purchase loans to buy a car and credit cards. These are things you would never be able to do with poor credit. You will also be free from the stress of having a lot of debt and having multiple creditors chase you. If you have more questions you’d like us to answer, view our Scottish Debt Help page or Contact Trust Deed Scotland today.

Call us on 01412210999 for any other Trust Deeds Questions!

Call 01412210999 for any other Trust Deeds questions you have. The team at Trust Deed Scotland are here to help and honestly, there are no Trust Deed questions that we’ve not answered before.
How Long Does A Trust Deeds Last?

If you have taken out a trust deed to help manage your debt, you’ll likely be wondering what happens when trust deeds finish. As your trust deed term comes to an end, you will enter what’s known as the trust deed discharge process. As long as all has gone to plan, this means you have reached the end of your agreement with your creditors and have paid off all your outstanding debt. So how does it all work?

How long does a trust deed last?

Typically, a Scottish Trust Deed will last for a term of four years. During this time, you will make regular monthly repayments to your creditors as you work to pay back your debt, sticking to a plan that’s been agreed in advance. We say “typically” because a trust deed term can sometimes last longer than 48 months which would be arranged prior to entering your trust deed. And you may find yourself in a position to pay off your debts earlier, such as through selling a property and releasing equity. It’s important to note, though, that both of these arrangements need to be formally agreed before the trust deed is set in stone.

What happens when you’ve completed your trust deed term?

After your trust deed is finished, you are discharged from it, as long as you have met the obligations agreed to at the start of the process. The discharge process should take around a month – if it’s taking longer, contact your insolvency practitioner to ask why. Once discharged, all debts included in your plan will be written off. This should reflect on your credit score within 3 months. If your debts are not shown as satisfied within this time, contact your creditors and ask them to update your credit file. You can now begin rebuilding your credit.

How long does a Trust Deed take to set up?

Normally, it takes between 35-56 days for your Trust Deed proposal to be drafted by the Insolvency Practitioner. This may change depending on the complexity of your case. The proposal is then passed to the creditors for approval, who may then take up to 14 days to approve. Depending on the length of your trust deed term, you may find it difficult to obtain credit for the next year or two and you may only be offered higher interest rates during this time. However, six years after your trust deed started it will no longer show on your credit file. If you’d like information about entering a Trust Deed, try our Trust Deed Debt Calculator to see how we could help.

How do people rebuild their credit scores after Trust Deeds?

  • Spread out applications for credit.
  • Get a credit card with as low interest as possible.
  • Make small monthly purchases on the credit card and clear them in full. This enables you to make sure you don’t build up debt again.
  • Make sure you are on the electoral role.
  • Check your credit file for any inaccuracies. If there are, you can ask the company in question to fix them.
  • Don’t take out joint finances with anyone with poor credit.
  • Ask for a notice of correction to be put on your credit file if you had a reason you could not make payments, for example, hospitalisation or redundancy. (These do not have to be taken into consideration but may make a difference to some lenders if you can justify late payments that have affected your credit).

What have others said about their trust deed discharge process?

Trust Deed Scotland has a 99% satisfaction rate. Don’t just take our word for it – here are what some of our customers have said about the process and how long does a trust deed last: “From the 1st initial call right through to signing the paperwork it was great to have the professionalism, help and reassuring assistance from Danielle and Deborah. They were both understanding of my situation and I highly recommend them both as well as Trust Deed Scotland.” Al, 5/5 – Al had a trust deed that lasted 48 months. “Excellent people put my mind at rest after many months of worry. Helpful, reassuring and friendly people!” Chris Forster, 5/5 – Chris looked at solutions DAS Scotland and Trust Deeds which lasted 4 years. After which his unaffordable debt was written off. Chris now enjoys a lift after debt. “I suffer from anxiety and find it difficult to contact people I don’t know. The team was fantastic with me, helping me and catering agents to my needs. They have helped me so much and now I don’t feel as anxious and I can answer my front door again without worrying.” Nataliemary, 5/5 Read our trust deed reviews and learn what everyone is saying about their Trust Deed Scotland experience to help you decide whether it‘s the right debt solution option for you. For more information on Protected Trust Deeds take a look at our guide to protected trust deeds. If you’re wondering how a trust deed works, you will also find our walk-through guide useful too. If you’re based in Scotland and are in need of debt advice, contact us for a confidential chat.